
TDS Payment FY 2026-27: New Section Codes
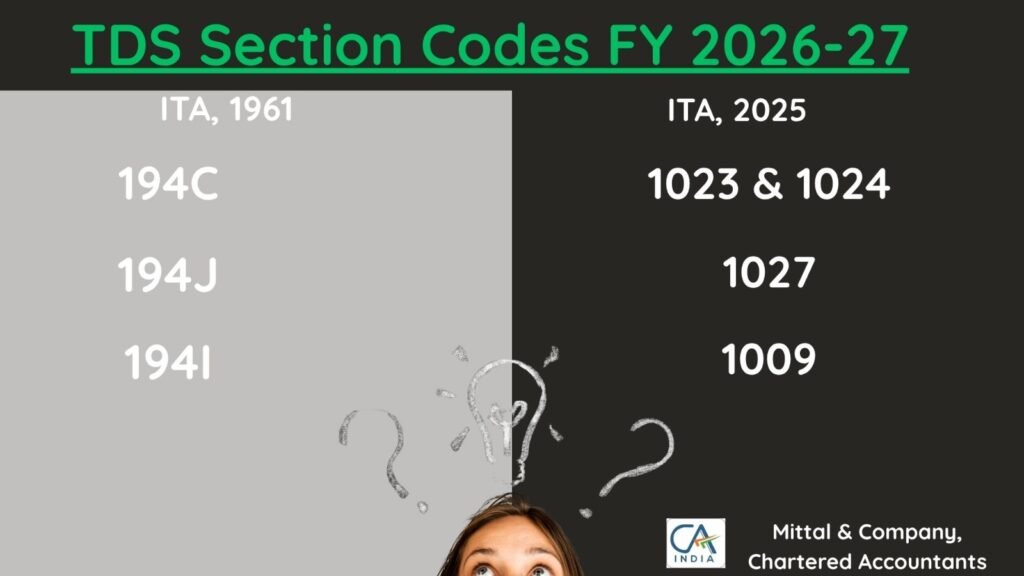
Introduction From FY i.e. TY 2026-27, the landscape of Tax Deducted at Source (TDS) compliance has undergone a major update with the introduction of new section codes. These codes are now mandatory for deductors to select while making TDS payments, ensuring precise categorization of transactions and improved reconciliation with returns. The change is aimed at eliminating ambiguity, strengthening audit trails, and aligning reporting with the revised Income-tax Act, 2025. Let’s go through the list of section codes! Section Codes- Income Tax Act, 2025 Salary: Section Rate Payment to Government employees other than Union Government employees – 392 – 1001 – Payment of Employees other than Government Employees – 392 – 1002 – Other than salary – resident payee/ deductee: Section Rate Payment of accumulated balance due to an employee – 392(7) – 1004 – Commission or brokerage – insurance – 393(1) [Table: Sl. No. 1(i)] – 1005 2% in case for Individual 10% in case for Others Commission or brokerage – others – 393(1) [Table: Sl. No. 1(ii)] – 1006 2% Rent on machinery etc. – specified person – 393(1) [Table: Sl. No. 2(ii).D(a)] – 1008 2% Rent other than machinery etc. – specified person – 393(1) [Table: Sl. No. 2(ii).D(b)] – 1009 10% Payment on any consideration, not being consideration in kind, under the agreement referred to in section 67(14). – 393(1) [Table: Sl. No. 3(ii)] – 1011 10% Payment of Compensation on Acquisition of Certain Immovable Property – 393(1) [Table: Sl. No. 3(iii)] – 1012 10% Income payable to a resident assessee in respect of Units of a specified Mutual Fund specified under Schedule VII [Table: Sl. No. 20 or 21] or units from the Administrator of the specified undertaking or units from specified company – 393(1) [Table: Sl. No. 4(i)] – 1013 10% Certain income in the form of interest from units of a business trust to a resident unit holder – 393(1) [Table: Sl. No. 4(ii)] – 1014 10% Certain income in the form of dividend from units of a business trust to a resident unit holder – 393(1) [Table: Sl. No. 4(ii)] – 1015 10% Certain income in the form of Renting from units of a business trust being a real estate investment trust to a resident unit holder – 393(1) [Table: Sl. No. 4(ii)] – 1016 10% Any income, other than that proportion of income which is exempt under Schedule V [Table: Sl. No. 2], in respect of units of an investment fund specified in section 224, payable to its unitholder – 393(1) [Table: Sl. No. 4(iii)] – 1017 10% Any income, in respect of an investment in a securitisation trust specified in section 221 to an investor – 393(1) [Table: Sl. No. 4(iv)] – 1018 10% Any income by way of Interest on securities – 393(1) [Table: Sl. No. 5(i)] – 1019 10% Any income by way of interest other than interest on securities, in case of deductee/payee is a senior citizen – 393(1) [Table: Sl. No. 5(ii).D(a)] – 1020 10% Any income by way of interest other than interest on securities, in case of deductee/payee is other than senior citizen – 393(1) [Table: Sl. No. 5(ii).D(b)] – 1021 10% Any income being interest other than interest on securities – 393(1) [Table: Sl. No. 5(iii)] – 1022 10% Any sum for carrying out any work (including supply of labour for carrying out any work) in pursuance of a contract between the contractor and a designated person – if contractor is individual or Hindu undivided family. – 393(1) [Table: Sl. No. 6(i).D(a)] – 1023 1% in case for Individual 2% in case for Others Any sum for carrying out any work (including supply of labour for carrying out any work) in pursuance of a contract between the contractor and a designated person – if contractor is a person other than individual or Hindu undivided family – 393(1) [Table: Sl. No. 6(i).D(b)] – 1024 1% in case for Individual 2% in case for Others Any sum by way of–– (a) fees for technical services (not being a professional services); or (b) royalty in the nature of consideration for sale, distribution or exhibition of cinematographic films; or (c) payee, engaged only in the business of operation of call centre – from Specified person – 393(1) [Table: Sl. No. 6(iii).D(a)] – 1026 2% Any sum by way of–– (a) fees for professional services; or (b) any sum referred to in section 26(2)(h) – from Specified person – 393(1) [Table: Sl. No. 6(iii).D(b)] – 1027 10% Any sum by way of remuneration or fees or commission by whatever name called, other than those on which tax is deductible under section 392, to a director of a company – from Specified person – 393(1) [Table: Sl. No. 6(iii).D(b)] – 1028 10% Any dividends (including on preference shares) declared – 393(1) [Table: Sl. No. 7] – 1029 10% Any sum under a life insurance policy, including the sum allocated as bonus on such policy, other than the amount not includible in the total income under Schedule II [Table: Sl. No. 2] – 393(1) [Table: Sl. No. 8(i)] – 1030 2% Any sum for purchase of any goods – 393(1) [Table: Sl. No. 8(ii)] – 1031 0.10% Payment to Specified Senior Citizen – 393(1) [Table: Sl. No. 8(iii)] – 1032 10% Any benefit or perquisite, whether convertible into money or not, arising from business or the exercise of a profession of any resident – 393(1) [Table: Sl. No. 8(iv)] – 1033 10% Sale of goods or provision of services by an e-commerce participant, facilitated by an e-commerce operator through its digital or electronic facility or platform. – any e commerce operator – 393(1) [Table: Sl. No. 8(v)] – 1035 0.10% Any sum by way of consideration for transfer of a virtual digital asset by other than Individual or Hindu Undivided Family – 393(1) [Table: Sl. No. 8(vi)] – 1037 1% Any income by way of winnings (other than winnings from Sl. No. 2 of the table at section 393(3))