New Income Tax Rules 2026: What Businesses, Professionals and Taxpayers Need to Review Now
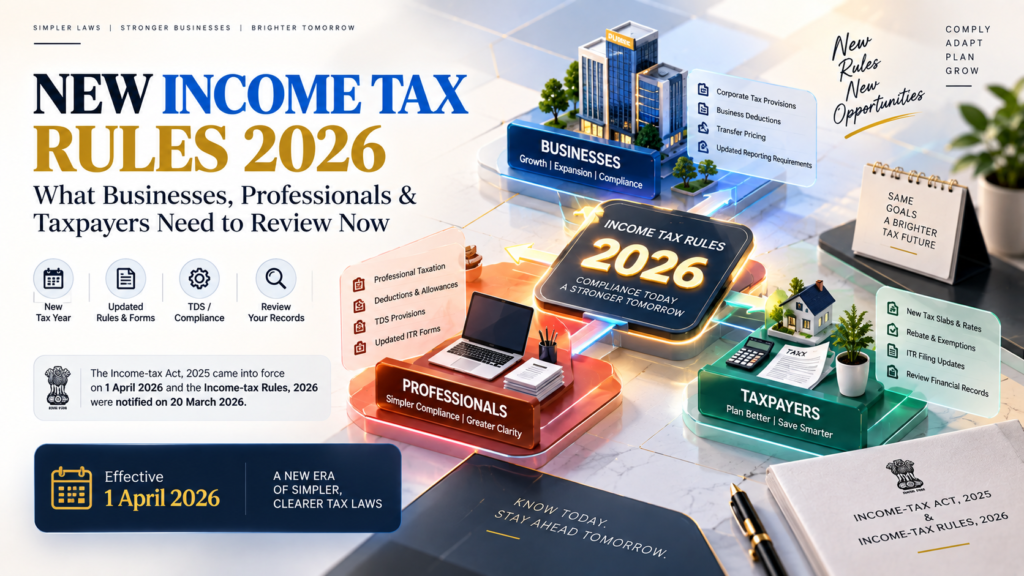
TL;DR 2026 is an important transition year for India’s income-tax system. The Income-tax Act, 2025 came into force from 1 April 2026, replacing the Income-tax Act, 1961 for the new tax framework. This means businesses, professionals and individual taxpayers need to understand more than just changes in tax rates. They also need to review their accounting systems, tax records, TDS processes, return filing procedures, notices, documentation and compliance workflows. The new framework also introduces changes in terminology and the structure of tax provisions. For taxpayers, the practical objective should be to identify which rules apply to the relevant tax year, update internal processes and avoid continuing with outdated assumptions from the earlier law. Why 2026 Is Different for Income-Tax Compliance The biggest change is the transition from the Income-tax Act, 1961 to the Income-tax Act, 2025. The new Act came into force on 1 April 2026. This creates an important distinction between tax periods. For income relating to the financial year ending 31 March 2026, taxpayers generally continue dealing with the earlier framework applicable to that period. For income earned from 1 April 2026 onward, the new Income-tax Act, 2025 becomes relevant. This means businesses should not treat all 2026 tax matters as if they fall under one set of provisions. Tax Year vs Earlier Assessment-Year Terminology One of the changes taxpayers need to understand is the shift toward the concept of a Tax Year. Under the new framework, the tax year generally corresponds to the financial year in which income is earned. For example: 1 April 2026 – 31 March 2027 = Tax Year 2026–27 This is different from the familiar earlier terminology where income earned during a financial year was generally assessed in the following assessment year. Businesses should therefore review the terminology used in: Accounting software Tax reports Internal MIS Tax invoices and documentation where relevant TDS systems Return-filing processes Tax notices and correspondence Professional tax workpapers Businesses Need to Review Their Accounting Systems The transition to the new Act makes accounting-system review particularly important. Businesses should check whether their accounting and tax software is updated for the new framework. Important areas include: Tax calculation TDS Advance tax Tax depreciation Deductions Tax return preparation Tax audit reporting Employee taxation Tax notices Financial reporting An outdated system can create errors even when the underlying accounting records are correct. Review Your Tax Calculation Method Businesses and professionals should review how tax liability is being calculated under the new framework. Tax calculation should consider: Applicable tax rates Tax regime Deductions Exemptions Business income Capital gains Other income TDS credits Advance tax Tax payments Applicable surcharge and cess Taxpayers should avoid relying on calculators or spreadsheets prepared under the previous law without verifying whether the underlying provisions are still applicable. Businesses Should Review Their TDS Process TDS is one of the areas where incorrect implementation can create recurring compliance problems. Businesses should review: TDS sections Applicable rates Deduction timing Payment timelines TDS returns Certificates PAN details Vendor classification Employee TDS Contractor payments Professional fees Rent Interest payments The accounting team should ensure that the TDS configuration in accounting or payroll software reflects the provisions applicable from the relevant tax year. Employee Payroll Also Needs Attention Companies should review their payroll systems after the transition to the new income-tax framework. Payroll teams should verify: Employee declarations Tax regime selection Salary components Perquisites Allowances Deductions TDS calculations Form 16 data Taxable benefits Employees should also review their salary structure and tax declarations instead of assuming that previous-year calculations automatically remain valid. Professionals Should Review Presumptive Taxation Professionals operating as independent consultants, freelancers or eligible professionals should review the provisions applicable to their income. Areas that may require attention include: Professional receipts Business expenses Books of account Presumptive taxation Tax audit applicability Advance tax TDS credits Return filing Professionals should not automatically carry forward the previous year’s tax treatment without checking the provisions applicable to the new tax year. Businesses Should Review Tax-Deductible Expenses Companies should review whether their expense classification and supporting documentation are adequate. Important areas include: Employee expenses Professional fees Interest Repairs Travel Advertising Business promotion Rent Depreciation Donations Related-party payments Statutory payments The accounting team should maintain proper supporting documentation for significant expenses. A tax deduction should not be assumed simply because an expense appears in the profit and loss account. Capital Gains Reporting Should Be Reviewed Individuals and businesses with investments should pay attention to the tax treatment of capital gains under the new framework. Taxpayers should maintain records for: Purchase date Purchase cost Sale date Sale consideration Expenses Securities transactions Property transactions Capital improvements TDS, where applicable Investment-related tax calculations should be based on the provisions applicable to the relevant tax year. AIS and TIS Still Matter Taxpayers should continue reviewing information appearing in their Annual Information Statement (AIS) and Taxpayer Information Summary (TIS). These records can contain information relating to: Interest income Dividend income Securities transactions Property transactions TDS TCS Other reported financial transactions A mismatch between AIS/TIS and the taxpayer’s own records should be investigated before filing the relevant return. Taxpayers should not automatically assume that every AIS entry is correct. Advance Tax Planning Becomes More Important Businesses and professionals should estimate tax liability during the year rather than waiting until year-end. Advance tax planning should consider: Current-year profits Capital gains Interest income Dividend income TDS already deducted Previous tax payments Expected deductions Business changes Regular tax projections can help identify underpayment before interest consequences arise. Review Your Tax Documents Businesses and professionals should maintain a structured tax-documentation system. Important records can include: Sales invoices Purchase invoices Expense bills Bank statements Investment statements Loan documents TDS certificates GST records Payroll records Property documents Capital asset records Previous tax returns Tax notices Audit reports Digital record-keeping can make future tax assessments and notices easier to manage. GST and Income-Tax Data Should Also Be Reconciled Businesses should not treat GST and income-tax compliance as completely separate systems. Differences can occur between: Books → GST returns → TDS