
Filing ITR-2 for FY 2025-26: Everything You Need to Know
Introduction Every year, many taxpayers get confused about which ITR form to file. A common mistake is filing ITR-1 (Sahaj) when in reality, their income profile requires ITR-2. This often leads to missing out on important disclosures; especially for non-residents, company directors, or individuals with capital gains and multiple house properties. Another overlooked aspect is the carry forward of previous year’s losses, which cannot be properly claimed if the wrong form is filed. Understanding the distinction is key to avoiding defective returns and ensuring full compliance. ✅ Who Can File ITR-2? ITR-2 is designed for taxpayers whose income does not fall under “Profits and Gains of Business or Profession.” It applies to: Salary/Pension Income – Whether from one employer or multiple, including allowances and perquisites. House Property Income – Covers rental income from one or more properties, including cases where you own more than two houses. Capital Gains – Short-term or long-term gains from sale of shares, mutual funds, property, or other capital assets. Other Sources – Includes interest income, winnings from lotteries, betting, gambling, racehorses, etc. Agricultural Income – If agricultural income exceeds ₹5,000. Special Cases: Non Residents Individuals who are directors in a company. Individuals who held unlisted equity shares during the year. Carry forward of previous year’s losses 🔄 Who Should File ITR-2 Instead of ITR-1? While ITR-1 (Sahaj) is meant for salaried individuals with income up to ₹50 lakhs, limited to one or two house properties, and no capital gains, certain taxpayers must switch to ITR-2. You should file ITR-2 instead of ITR-1 if: You own more than two house properties or earn rental income from multiple properties. You have capital gains from sale of shares, mutual funds, property, or other assets. You have carry forward of previous year’s losses You have agricultural income exceeding ₹5,000. You are a non-resident with income in India. You are a company director or hold unlisted equity shares. Your income includes lottery winnings, betting, gambling, or racehorses. 👉 In short, if your income profile goes beyond the “simpler” categories covered under ITR-1, you must opt for ITR-2 to ensure proper compliance. 🚫 Who Cannot File ITR-2? ITR-2 is not applicable if your income includes: Profits and gains from business or profession. Income such as interest, salary, bonus, commission, or remuneration received from a partnership firm, taxable under “Profits and Gains of Business or Profession.” Carry forward of business loss from any previous years Speculation income In such cases, you must opt for ITR-3 instead. 📂 Documents Required for ITR-2 Filing To ensure smooth filing, keep the following documents ready: Form 16 – For salaried individuals, issued by the employer. Form 16A – For interest income where TDS is deducted. Form 26AS & AIS – Comprehensive tax credit statements available on the e-filing portal. Rent Receipts – For HRA claims if not submitted to employer. Capital Gains Statement – Profit/loss summary of share or securities transactions. Bank Passbook & FDRs – To calculate interest income. House Property Details – Tenant information, municipal tax receipts, loan interest details. Loss Documents – Proof of current year losses for set-off. Previous Year’s ITR – For carrying forward losses. Deduction Proofs (80C, 80D, 80G, 80GG, etc.) – Insurance premiums, tuition fees, donation receipts, rent receipts, etc. ⚡ Precautions to Avoid Issues To prevent rejection or delays in refunds: Link Aadhaar with PAN – Mandatory for most taxpayers. Pre-validate your bank account – Ensures smooth refund credit. Select the correct ITR form – Filing with the wrong form leads to a defective return. File within due dates – Avoid penalties and interest. Verify your return promptly – E-verification is the fastest and most reliable option. Conclusion ITR-2 is designed for taxpayers with diverse income streams beyond business or profession. With detailed disclosures and stricter compliance requirements, preparation is key. By keeping the right documents ready, choosing the correct form, and verifying your return on time, you can ensure a seamless filing experience and avoid unnecessary hassles. Filing smart today means peace of mind tomorrow. For more information, please feel free to connect with us on info@camittal.com or 9096623634. Disclaimer: This blog is for educational purposes only and should not be considered professional accounting, tax, or legal advice. Please consult a qualified professional before making financial decisions. BLOG BY: Mittal & Co.
Data-Driven Tax Scrutiny in 2026: Why the Government Knows More Than You Think
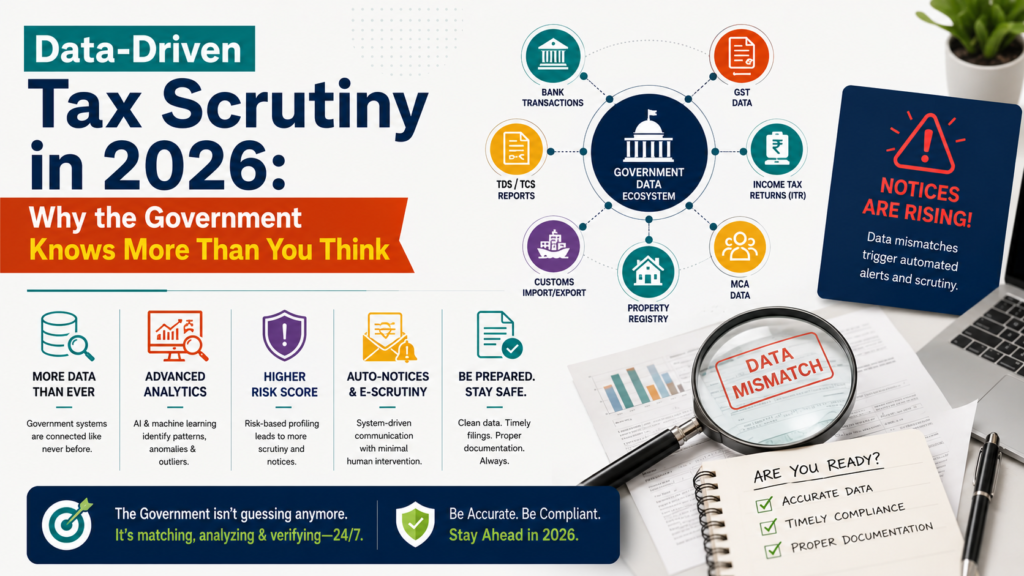
TL;DR India’s tax ecosystem in 2026 is heavily data-driven. The government now uses AI systems, GSTN analytics, AIS/TIS reporting, banking integrations, e-invoicing, and digital payment tracking to identify mismatches automatically. Businesses with inconsistent GST filings, unexplained cash flow, incorrect ITC claims, or underreported income are increasingly receiving scrutiny notices. Proactive compliance, reconciliation, and expert advisory are now essential. The New Era of AI-Powered Tax Surveillance For years, tax scrutiny in India depended heavily on manual assessments and selective investigations. That landscape has changed dramatically. In 2026, tax departments no longer rely only on declared figures in returns. They now compare data from multiple systems simultaneously: GST returns Income tax filings AIS/TIS records TDS filings E-invoices Banking transactions UPI and digital payment trails MCA and ROC filings Customs and import-export data The result is a highly connected compliance ecosystem where inconsistencies are detected faster than ever. Businesses that previously assumed small discrepancies would go unnoticed are now facing automated alerts and notices. What “Data-Driven Tax Scrutiny” Actually Means Data-driven scrutiny refers to the use of technology, analytics, and AI-based risk assessment to identify suspicious tax behavior. Instead of randomly selecting taxpayers, authorities now use algorithms to identify: High-risk transactions Unusual input tax credit claims Mismatched turnover Suspicious vendor chains Fake invoicing patterns Underreported income GSTN Analytics The GST Network now performs advanced invoice-level matching. If your: GSTR-1, GSTR-3B, E-way bills, E-invoices, Vendor filings, do not align properly, the system can flag the discrepancy automatically. This is one of the major reasons GST notices are increasing across India. AIS & TIS Reporting Annual Information Statement (AIS) and Taxpayer Information Summary (TIS) have become powerful scrutiny tools. The Income Tax Department can now see: High-value banking transactions Mutual fund investments Stock market activity Foreign remittances Credit card spends Property purchases Interest income TDS/TCS data If your filed income does not align with financial behavior, the mismatch becomes visible instantly. Banking & Digital Payment Tracking The rapid adoption of: UPI, POS machines, Payment gateways, Digital wallets, has significantly reduced untraceable transactions. Businesses operating heavily in cash but showing low digital turnover patterns inconsistent with industry benchmarks may attract scrutiny. MCA, ROC & PAN Integration Government departments increasingly share information across platforms. For example: ROC turnover data may be compared with GST turnover PAN-linked banking transactions may be checked against ITR disclosures TDS deductions may be matched with declared income This interconnected approach leaves far fewer gaps in reporting. Why Tax Notices Are Increasing in 2026 Real-Time Data Matching Earlier, mismatches could remain unnoticed for years. Now, automated systems detect: ITC mismatches Vendor inconsistencies Duplicate invoices Delayed filings Suspicious refund claims in near real time. Automated Risk Profiling Businesses are increasingly assigned risk scores based on: Filing behavior Industry patterns Transaction size Compliance history Vendor network quality Higher-risk profiles are more likely to receive: GST notices Income tax scrutiny Audit requests Compliance verification communications E-Invoicing Expansion The government’s continued expansion of e-invoicing has dramatically increased transaction transparency. Authorities can now track: Invoice generation timing Invoice amendments Supply chain patterns Tax liability consistency This reduces opportunities for invoice manipulation. UPI & Digital Trail Visibility Digital payments create permanent records. Large unexplained credits, frequent high-value transfers, or inconsistent reporting between bank statements and tax filings can quickly trigger automated checks. Common Triggers That Invite Scrutiny Trigger Possible Impact GSTR-1 and GSTR-3B mismatch GST notice Excess ITC claims ITC reversal scrutiny High cash deposits Income tax verification Low profit margins inconsistent with industry Assessment risk Vendor non-compliance ITC denial Incorrect HSN/SAC usage GST classification dispute Delayed return filing Higher scrutiny probability Mismatch between AIS and ITR Income tax notice How GST and Income Tax Departments Cross-Verify Data One of the biggest misconceptions among businesses is believing GST and Income Tax departments operate independently. In reality, cross-verification has become increasingly sophisticated. For example: Data Source Cross-Checked Against GST turnover Income tax turnover E-invoices GSTR filings Bank transactions Declared business receipts TDS entries Revenue disclosures ROC filings Tax returns Vendor GST filings ITC claims This integrated structure allows authorities to identify inconsistencies rapidly. Red Flags Businesses Often Ignore Many scrutiny cases arise not from fraud, but from negligence. Common examples include: Claiming ITC from non-compliant vendors Ignoring reconciliation processes Incorrect expense classification Filing returns without verification Multiple revisions and corrections Sudden turnover spikes Unrealistic profit disclosures Businesses often underestimate how visible these patterns have become. Practical Compliance Checklist for Businesses Monthly Compliance Actions Reconcile GSTR-1 and GSTR-3B Verify vendor GST compliance Match purchase registers with ITC claims Review bank transaction consistency Quarterly Actions Conduct internal GST review Validate e-invoice reporting Review TDS compliance Analyze AIS/TIS entries Annual Actions Perform full tax reconciliation Compare ROC and GST turnover Validate expense documentation Conduct tax risk assessment What to Do If You Receive a Notice Receiving a notice does not automatically mean wrongdoing. However, delayed or incorrect responses can escalate matters. Recommended Steps Review the notice carefully Identify the exact mismatch or issue Gather supporting documentation Reconcile all relevant returns Respond within deadlines Consult a qualified tax professional Avoid: Ignoring notices Submitting incomplete replies Providing inconsistent explanations How Professional Tax Advisors Reduce Risk Modern compliance is no longer just about filing returns. Professional CA firms help businesses: Conduct proactive reconciliations Detect risk indicators early Maintain audit-ready documentation Handle GST and income tax notices Improve compliance systems Reduce litigation exposure For growing businesses, this proactive approach can significantly reduce operational and financial stress. Mittal & Co. provides GST compliance, tax advisory, audits, registrations, accounting support, and business compliance services for businesses and professionals in Pune and across India. Conclusion Tax scrutiny in India has entered a new technological era. In 2026, government systems can connect GST filings, banking data, AIS records, e-invoices, TDS filings, and digital payment trails with unprecedented efficiency. Businesses that rely on outdated compliance practices face increasing exposure to notices and investigations. The safest strategy is no longer reactive compliance. It is proactive transparency, regular reconciliation, strong documentation, and professional oversight. As regulatory systems become smarter, businesses must become more