Beyond the Headlines: E-Invoicing for RCM, Credit Clarifications and Other GST Changes You Should Know
GST UPDATE | PART 2 | NOVEMBER 2026 The quieter changes in the November 2026 GST package that matter for cash flow and compliance In our earlier update, we covered the headline GST changes that took effect on 1 November 2026: easier post-sale discounts, 90% provisional refunds for inverted duty, relief for small exporters, the scrap and waste rules and the registration overhaul. The same package, issued after the 57th GST Council meeting, also contained a number of less publicised changes. The most important of them is a new e-invoicing obligation for reverse charge purchases from January 2027. Others settle long-standing credit questions, change how e-commerce delivery is taxed and improve refund cash flow. We have listed them below in order of practical importance. The changes at a glance Change Effective from Who should take note E-invoicing for RCM purchases and import of services 1 January 2027 Businesses above the e-invoice threshold ITC on demo vehicles, used cars; rate clarifications Circulars of October 2026 Auto dealers, toy, paper and fertiliser trades E-commerce operator liable for delivery services by unregistered providers 1 November 2026 E-commerce platforms, delivery partners 1.5x domestic-value cap on export refunds removed 1 November 2026 Exporters under LUT Capital goods ITC in refunds; Rule 86A procedure 1 April 2027 Manufacturers; all taxpayers Refund acknowledgement in 10 days; system-generated provisional refund 1 November 2026 All refund claimants Inverted duty refund now includes ITC on input services 1 November 2026 Manufacturers with accumulated ITC 1. E-invoicing extended to RCM purchases and import of services Until now, e-invoicing applied to B2B supplies and exports made by taxpayers above the notified turnover threshold. Purchases on which the recipient pays tax under reverse charge were documented through self-invoices prepared outside the e-invoice system. What has changed: Notification 04/2026-Central Tax extends e-invoicing, from 1 January 2027, to: supplies received from unregistered persons on which the recipient pays tax under reverse charge; and import of services. In these cases, the recipient will generate an IRN for the self-invoice on the Invoice Registration Portal. To support this, the e-invoice schema (version 1.2 of FORM GST INV-01) adds two new supply types: RCMDOM for domestic reverse charge purchases and RCMIMP for import of services. GSTN has already opened a sandbox for testing. Use the next two months well Speak to your billing or ERP provider now about RCM self-invoice support under schema 1.2. Map your recurring RCM purchases (for example, services from unregistered vendors) and import of services transactions, and test them on the sandbox before 1 January 2027. 2. Clarifications that may unlock credit ITC on demo vehicles (Circular 262/08/2026-GST) CBIC has clarified that authorised dealers can claim ITC on demo vehicles under the dealer-agency model, even where the manufacturer sells directly to the customer and the dealer acts as its agent. Dealers who had held back such credit should review their position. Classification and ITC clarifications (Circular 265/11/2026-GST) Used motor vehicles (margin scheme): the bar on ITC applies only to tax on second-hand vehicles bought for resale. Credit on spares, repairs, rent, technology and marketing services is available, subject to the usual conditions. Toys (heading 9503): non-electronic toys at 5% and electronic toys at 18%. Sublimation paper: classified under heading 4809 at 18%; past periods regularised on an “as is where is” basis. Seaweed extract bio-stimulants: classified as fertilisers under heading 3101 where registered under the Fertiliser Control Order; past periods regularised on an “as is where is” basis. 3. Delivery services through e-commerce operators Notification 09/2026-Central Tax (Rate) revises the services for which an e-commerce operator pays tax under Section 9(5), with effect from 1 November 2026. A new entry covers delivery services supplied through an e-commerce operator, replacing the earlier entry for “local delivery”. Postal and courier services are excluded. The operator is liable only where the delivery service provider is not liable for registration under Section 22(1). Such delivery services attract GST at 5% without input tax credit (Notification 06/2026-Central Tax (Rate)). Where the provider is liable for registration, the provider pays tax itself at the same rate. E-commerce platforms that onboard delivery partners should update their onboarding checks, tax codes and invoicing flows. 4. Export refunds: the 1.5x cap goes Rule 89(4)(C) limited the value of zero-rated goods considered for refund to 1.5 times the value of similar goods supplied domestically. This cap often led to disputes and reduced refunds. It has been omitted from 1 November 2026. 5. Coming on 1 April 2027: capital goods in refunds and a fair process for ITC blocking Notification 05/2026-Central Tax also contains two changes that take effect from 1 April 2027. They are worth planning for now. a) Capital goods ITC in refunds From 1 April 2027, ITC on capital goods attributable to inverted-rated or zero-rated (LUT) supplies will be included in the refund formula, spread at 1/60th per month over 60 months. Capital-intensive manufacturers and exporters should start tracking capital goods credit by product line. b) Blocking of ITC under Rule 86A Blocking of the electronic credit ledger will require a formal order in DRC-26, will last up to one year unless lifted earlier, and can be objected to in DRC-27, with a hearing and an order in DRC-28. This brings much-needed process and transparency to a power that has often been used without notice. 6. Faster refund processing From 1 November 2026, the refund rules also change how quickly claims move through the system: Rule 90: the officer must acknowledge the refund application or point out deficiencies within 10 days, instead of 15. If neither happens, the application is deemed acknowledged. Rule 91: the portal may generate the provisional refund order (RFD-04) within 3 working days of acknowledgement, based on system risk assessment. Rule 92: final sanction orders and payment advices can now be generated by the portal, enabling automated processing and adjustment against outstanding demands. Order of debit: Refunds sanctioned are now debited first from IGST credit, and then equally from CGST and SGST/UTGST credit (amended Rule 89(3)). 7.
Companies Act Annual Filing Deadlines for FY 2025-26: Updated for MCA Circular 05/2026
AOC-4, MGT-7, ADT-1, CRA-4, MSME-1 and more — what is due, what has been relaxed, and how to plan the rest of the season
Deferred Tax Computation for Companies: Temporary Differences, Tax Base and Applicable Rates
How AS 22 and Ind AS 12 work, the step-by-step method, and a fully worked example under the section 115BAA regime
ITR-6 for Companies, FY 2025-26 (AY 2026-27): Key Updates and Practical Points
ITR-6 for AY 2026-27: due dates, key form changes, tax rates and a practical filing checklist for companies.
57th GST Council Meeting: Key ITC and Return Updates
The 57th GST Council meeting on 8 October 2026 focused on process reforms. Here are the key ITC and return changes for businesses.
GST Registration in Multiple States Just Got Simpler: Understanding the New Multi-State Registration Option
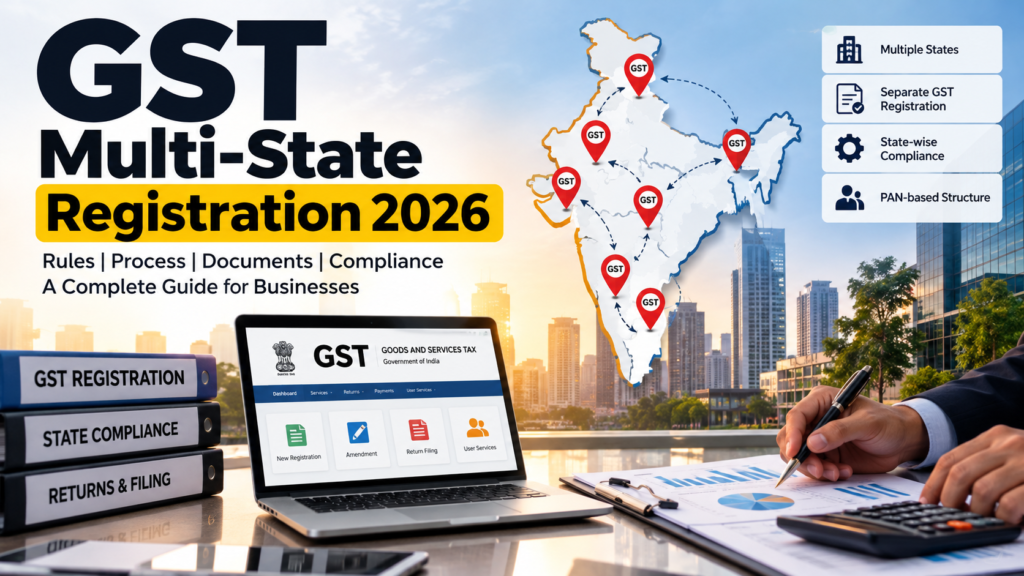
GST Update • October 2026 Expanding into a new State is an exciting milestone for any business – a new branch, a new warehouse, a new factory. Until now, though, it also meant a familiar chore on the GST Portal: filling in the same company details, director details and signatory details again and again, once for every State. That is now changing. With effect from 1 October 2026, the GST Common Portal offers a new “Multi-State Registration” option. Businesses that need GST registration in more than one State or Union Territory under the same PAN can now start all those applications together, through one common flow. Here is what the facility does, what it does not do, and how to make the most of it. What is the Multi-State Registration facility? The portal home page now carries a separate Multi-State Registration option alongside the regular new-registration route. Instead of opening a fresh application for each State, you select all the States/UTs you need in one go, verify once, and receive a single Master TRN (Master Temporary Reference Number). Common information is entered once against this Master TRN. When it is submitted, the portal generates individual TRNs for each selected State, carrying that common data forward. You then complete only the State-specific details for each application. How the process works Open the GST Portal and choose Multi-State Registration. Select every State/UT where registration is actually required. Enter basic details – legal name, PAN, e-mail and mobile – and complete OTP verification. A Master TRN is generated. Fill in the Common Registration Information – business details, promoters/partners, authorised signatory, authorised representative and goods/services. Submit the Master TRN (current portal guidance indicates a 15-day window for this). Separate State-wise TRNs are generated with the common data pre-filled. Complete each State application – place of business, documents and Aadhaar authentication – and submit. Each State processes its application independently and, on approval, issues its own GSTIN. What you enter once, and what you still enter State-wise Entered once (via Master TRN) Completed separately for each State Business details – legal name, PAN, constitution Principal place of business Promoters / partners / directors Additional places of business Authorised signatory Premises proof – rent agreement, ownership or electricity documents, NOC Authorised representative Aadhaar authentication, where applicable Goods and services (HSN / SAC) State-level verification and approval The pre-filled common details remain editable within each State application, so any State-specific variation can still be accommodated. What has not changed The new option is a procedural convenience. The legal framework under GST continues exactly as before, and it helps to keep these points clear: One GSTIN per State, not one for India. Each State/UT approved still gets its own GSTIN. A Master TRN is only an application reference. Distinct persons. Under Section 25(4) of the CGST Act, each registration of the same PAN continues to be a distinct person – so supplies between your own branches, cross-charge and ISD considerations remain as they are. ITC stays registration-wise. Credit available in one State’s registration does not become available to another State’s registration merely because both were created through a common application. Compliance stays State-wise. Returns, tax payments, e-invoicing, e-way bills, reconciliations and amendments continue GSTIN by GSTIN. Who can use it? The facility is presently available to Normal Taxpayers only. Specialised registration categories – such as composition taxpayers, casual taxable persons, non-resident taxable persons, TDS/TCS registrations, Input Service Distributors and OIDAR suppliers – should continue with their existing registration routes. Also note that one Master TRN supports one registration per State. If you need an additional registration within the same State (for example, a separate registration for another place of business), that is to be applied for through the regular procedure. First things first: do you actually need a registration there? The ease of ticking several States at once makes it tempting to register everywhere. Before you do, it is worth confirming where registration is legally required. Having customers in a State – or selling goods or services into it – does not by itself require you to register in that State. Broadly, a supplier registers in the States from which it makes taxable supplies. Every additional GSTIN brings its own returns, reconciliations and annual compliance, so registering only where required keeps your compliance load lean. Example: A Pune-based IT consultancy billing clients in Bengaluru, Delhi and Chennai from its Pune office generally needs only its Maharashtra registration. If it opens an operational office in Bengaluru from which services are supplied, a Karnataka registration becomes necessary – and that is exactly when the Multi-State option (for multiple new States together) becomes useful. A quick checklist before you apply Map the States where registration is genuinely required, based on where you have a fixed establishment or supply from. Verify that the legal name and constitution match PAN (and MCA records, for companies and LLPs). Double-check the common information carefully – since it flows into every State application, a single error gets multiplied. Keep State-wise premises documents ready: rent or lease agreement, ownership proof, recent electricity bill and consent/NOC from the owner. Ensure promoters and the authorised signatory are available for Aadhaar authentication in each application. Plan post-registration set-up: GSTIN-wise invoicing series, e-invoice and e-way bill configuration, and the treatment of common input services (ISD or cross-charge). Looking ahead This facility reflects a steady move towards simpler, more standardised GST registration. The simplified registration scheme for small and low-risk applicants has been in operation since November 2025, and further standardisation of documentation across States is on the GST Council’s agenda. For growing businesses, the direction is clearly towards less paperwork and quicker onboarding. How we can help Whether you are expanding into one new State or rolling out across several, Mittal & Company can help you identify where registration is required, prepare and file applications through the new Multi-State route, and set up State-wise compliance from day one – so your expansion stays smooth and focused on growth. Conclusion:
Tax and ROC Compliance After the ITR Season: What Businesses Need to Complete Next
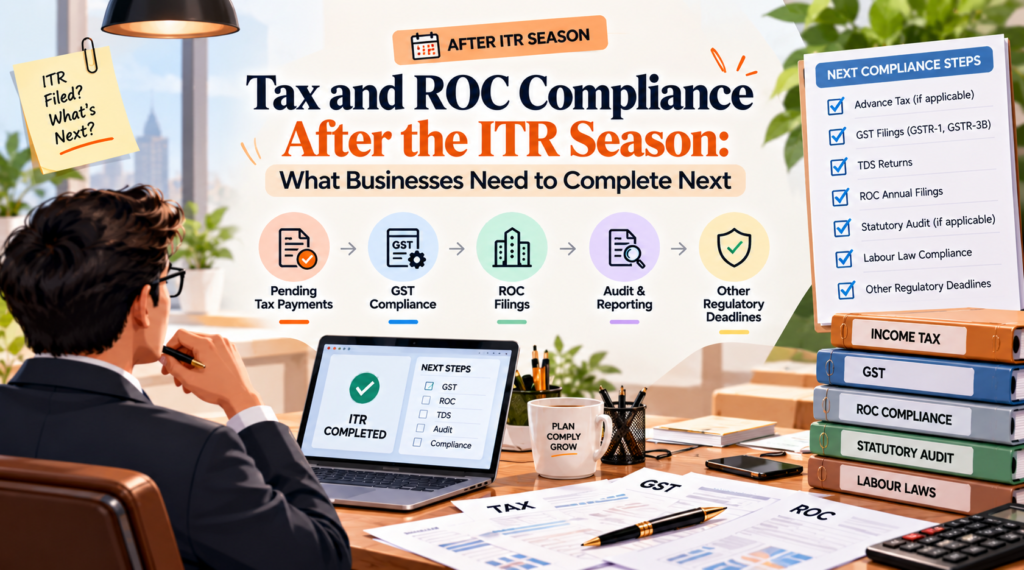
TL;DR For businesses, completing the income-tax return is only one part of the annual compliance cycle. After the ITR season, companies and other businesses may still need to address tax audit requirements, AGM compliance, financial-statement filing, annual returns, TDS reconciliation, GST reconciliation, director-related filings and other ROC obligations. The 2026 compliance cycle is particularly important because the Income-tax Act, 2025 has come into force from 1 April 2026, while tax matters relating to FY 2025–26 continue to be governed by the earlier Income-tax Act, 1961. The Income Tax Department specifically confirms that tax-audit reports for FY 2025–26/AY 2026–27 continue to use the old Act’s prescribed forms even when filed after 1 April 2026. For companies, the next major focus should be completing the AGM and subsequent MCA filings, while keeping tax, GST, TDS and corporate records properly reconciled. ITR Filing Does Not End Business Compliance Many business owners treat the filing of the income-tax return as the final compliance activity of the year. In reality, several obligations can continue after the ITR is filed. Depending on the business structure, the post-ITR period may involve: Tax audit Annual General Meeting Financial-statement filing with ROC Annual return filing TDS reconciliation GST reconciliation Director-related filings Auditor-related compliance Board documentation Statutory registers FEMA or RBI reporting Other industry-specific compliance The exact requirements depend on whether the entity is a private limited company, public company, LLP, partnership firm, proprietorship or another form of business. 1. Check Whether Tax Audit Compliance Is Complete Businesses should first confirm whether their tax-audit obligation has been completed. For FY 2025–26, the Income Tax Department states that the tax-audit report continues to be governed by the Income-tax Act, 1961 because the audit relates to AY 2026–27, even if the report is filed after 1 April 2026. For the relevant FY 2025–26 tax-audit cycle, the Department confirms the applicable thresholds remain: Business turnover exceeding ₹1 crore ₹10 crore threshold where cash receipts and cash payments each do not exceed 5% of the relevant totals Professional receipts exceeding ₹50 lakh Certain taxpayers opting out of presumptive taxation The Department states that the tax-audit report for AY 2026–27 is due on 30 September 2026 in the applicable cases. Businesses should therefore verify whether their audit report has been: Prepared Reviewed Signed Filed Properly retained with supporting records 2. Understand Which Income-Tax Act Applies 2026 requires particular care because there is a transition between two income-tax frameworks. The Income-tax Act, 2025 applies from 1 April 2026. However, transactions and compliance relating to earlier periods do not automatically shift to the new Act. For example, the Income Tax Department confirms that a tax-audit report for FY 2025–26 / AY 2026–27 continues under the Income-tax Act, 1961. Businesses should therefore avoid mixing: FY 2025–26 / AY 2026–27 with Tax Year 2026–27 when preparing compliance documents. This distinction becomes particularly important for tax audits, assessments, notices, carried-forward losses and historical tax matters. 3. Prepare for the Annual General Meeting For companies, the AGM is one of the major compliance events following the financial year-end. The AGM provides the formal platform for matters such as consideration of financial statements, auditor-related matters and other business required under the Companies Act. Before the AGM, companies should review: Financial statements Board’s Report Auditor’s Report Directors’ disclosures AGM notice Attendance records Ordinary business Special business, where applicable Shareholder approvals Minutes and supporting documents The AGM should not be treated as merely a meeting conducted to satisfy a deadline. The company’s underlying records should be ready before the meeting. 4. ROC Filing Comes After the AGM Once the financial statements are adopted and the annual return information is finalised, the company generally needs to complete the applicable ROC filings. Two major annual filings are: AOC-4 AOC-4 is used for filing financial statements and related documents with the Registrar. MCA identifies AOC-4 as the form for filing financial statements and other documents with the Registrar. MGT-7 / MGT-7A The annual return is generally filed in MGT-7, while eligible OPCs and small companies use MGT-7A. MCA’s rules specify that every company files its annual return in MGT-7 except an OPC and small company, which file MGT-7A from FY 2020–21 onwards. The exact filing deadline depends on the applicable provisions and the date of the AGM. 5. Do Not Confuse AOC-4 With MGT-7 This is a common compliance mistake. The two filings serve different purposes. AOC-4: Primarily relates to the company’s financial statements and associated documents. MGT-7 / MGT-7A: Relates to the company’s annual return and corporate information. A company may need to complete both. Therefore, completing one does not automatically mean that the annual ROC compliance cycle is complete. 6. Review Auditor-Related Compliance Companies should also verify their auditor-related records. Depending on the circumstances, businesses may need to review: Auditor appointment Auditor consent Eligibility Appointment documentation ADT-1 compliance, where applicable Auditor’s report Changes in auditor details MCA identifies ADT-1 as the form used for information to the Registrar regarding appointment of an auditor. Companies should ensure that auditor records are consistent across corporate documents and MCA filings. 7. Reconcile TDS Before Closing the Compliance Cycle Even after the ITR is filed, TDS records should be reviewed. Businesses should reconcile: Books → TDS ledger → TDS returns → Form 26AS/AIS → Tax credit Check for: Missing deductions Incorrect PAN Wrong TDS rates Short deduction Excess deduction Incorrect challan details Unmatched TDS credits Vendor disputes A mismatch discovered after ITR filing should not simply be ignored. The business should identify the reason and take the appropriate corrective action. 8. Reconcile GST and Income-Tax Turnover Another important post-ITR exercise is comparing GST turnover with financial statements and income-tax records. Businesses should review: Sales as per books GST turnover GSTR-1 GSTR-3B Annual GST records, where applicable Income-tax turnover Credit notes Debit notes Advances Exempt supplies Export turnover Not every difference is automatically an error. Timing differences, accounting treatment and the nature of supplies can explain legitimate variations. However, material unexplained differences should be investigated and documented. 9. Review
FLA Return 2026: Who Needs to File It and What Businesses Should Check Before Submission
TL;DR The FLA Return (Annual Return on Foreign Liabilities and Assets) is an RBI reporting requirement for eligible Indian entities that have received Foreign Direct Investment (FDI) or made Overseas Direct Investment (ODI). The return is submitted online through the RBI’s FLAIR portal. The annual filing deadline is generally 15 July each year. For the 2026 filing cycle, businesses should ensure that their foreign investment, financial statements, shareholding and other relevant information are properly reconciled before submission. RBI guidance confirms that the annual FLA return is mandatory for Indian companies that have received FDI and/or made direct investment abroad. What Is an FLA Return? FLA stands for Foreign Liabilities and Assets. The FLA Return is an annual return submitted to the Reserve Bank of India (RBI) to report information relating to an entity’s foreign liabilities and assets arising from foreign investment. It is primarily a statistical and regulatory reporting requirement under the foreign-exchange framework. The information reported can cover areas such as: Foreign direct investment received in India Direct investment made outside India Foreign liabilities Foreign assets Shareholding information Financial performance Other relevant foreign-investment information The return is filed electronically through the RBI’s FLAIR system. RBI guidance states that eligible entities must submit the annual FLA return through the online web-based portal. Who Needs to File the FLA Return? The FLA Return is generally applicable to Indian entities that have: Received foreign direct investment, or Made direct investment outside India RBI guidance specifically states that annual FLA reporting is mandatory for Indian companies that have received FDI and/or made direct investment abroad. This means businesses should not assume that FLA reporting applies only to large companies. A company with foreign shareholding or an overseas investment may also need to examine whether FLA reporting applies to it. Does FLA Filing Apply to LLPs? LLPs can also have FLA reporting obligations where the relevant foreign investment or overseas investment conditions are met. RBI reporting guidance specifically provides for LLPs in the FLA return and notes that, because LLPs do not have a 21-digit CIN, a prescribed format can be used in the CIN field while filing. Therefore, an LLP with foreign investment should not automatically assume that the absence of a CIN removes its FLA reporting requirement. What Is the FLA Return Deadline? The annual FLA Return is generally required to be submitted by 15 July every year. RBI guidance specifies July 15 as the annual submission deadline. For businesses preparing their annual compliance calendar, this deadline should be tracked separately from: Income-tax return deadlines GST return deadlines MCA filings Tax audit Statutory audit ODI reporting Other FEMA compliances FLA reporting is an RBI/FEMA-related compliance and should not be confused with an income-tax or MCA return. What Information Is Reported in an FLA Return? The exact information required depends on the entity and its foreign investment position. Businesses may need to provide information relating to: Company Details Basic information such as: Name of entity PAN CIN or applicable identification details Registered office details Contact information Nature of business Foreign Investment Details Information regarding: Foreign investors Country of investor Shareholding Investment amount Equity participation Other relevant foreign liabilities Overseas Investment Where applicable, information regarding investments made outside India may also need to be reported. This can include: Overseas subsidiaries Overseas joint ventures Overseas associates Equity investment abroad Other reportable overseas investment positions Financial Information The return also requires relevant financial information. Businesses should therefore keep their audited or finalized financial statements available while preparing the return. What Businesses Should Check Before Filing FLA Return 2026 Preparing the return should not be treated as simply entering figures into an online form. The information should first be reconciled with the company’s records. 1. Reconcile Foreign Shareholding Check the company’s current foreign shareholding against: Share register Cap table Financial statements Share allotment records Transfer records FDI reporting records Any difference should be investigated before the FLA return is submitted. 2. Verify FDI Information Review previous FDI-related filings and transaction records. This may include information relating to: Share issuance Share transfers Foreign investors Capital received Conversion of instruments Other relevant foreign-investment transactions The FLA return should be consistent with the underlying records. 3. Check Financial Statements Financial information reported in the FLA return should be reconciled with the entity’s books and financial statements. Businesses should keep ready: Balance sheet Profit and loss statement Notes to accounts Investment schedules Fixed asset records Other relevant financial information Using estimated figures without proper reconciliation can create avoidable reporting problems. 4. Review Overseas Investments If the Indian entity has made investments outside India, review the relevant records before filing. Check: Overseas entity name Country Investment amount Ownership percentage Nature of investment Previous reporting Current financial position The company’s accounting records should agree with the information being reported. 5. Check Previous-Year FLA Filing Businesses that have filed FLA returns previously should compare the new return with the previous year’s submission. Look for unusual changes in: Foreign shareholding Foreign liabilities Foreign assets Investment values Revenue Net worth Overseas investments Large changes should have a clear accounting or transaction-related explanation. FLA Return and Audited Financial Statements One of the most important checks is consistency between the FLA return and financial statements. For example, if foreign investment information appears differently in the balance sheet, shareholding records and FLA return, the company should investigate the difference. The FLA return should be prepared using reliable financial data rather than treating it as a standalone compliance form. Where the accounts are still under finalisation, businesses should follow the applicable RBI reporting requirements and ensure the information submitted is accurate and supportable. What If There Was No Foreign Transaction During the Year? Businesses should not automatically assume that no new foreign transaction means no FLA reporting obligation. For example, an entity may have received FDI in an earlier year and continue to have foreign investment outstanding. The reporting requirement should therefore be assessed based on the entity’s applicable foreign-investment position and RBI requirements rather than only looking at
GST Compliance for Small Businesses: What Changes When Your Turnover Crosses the Registration Threshold
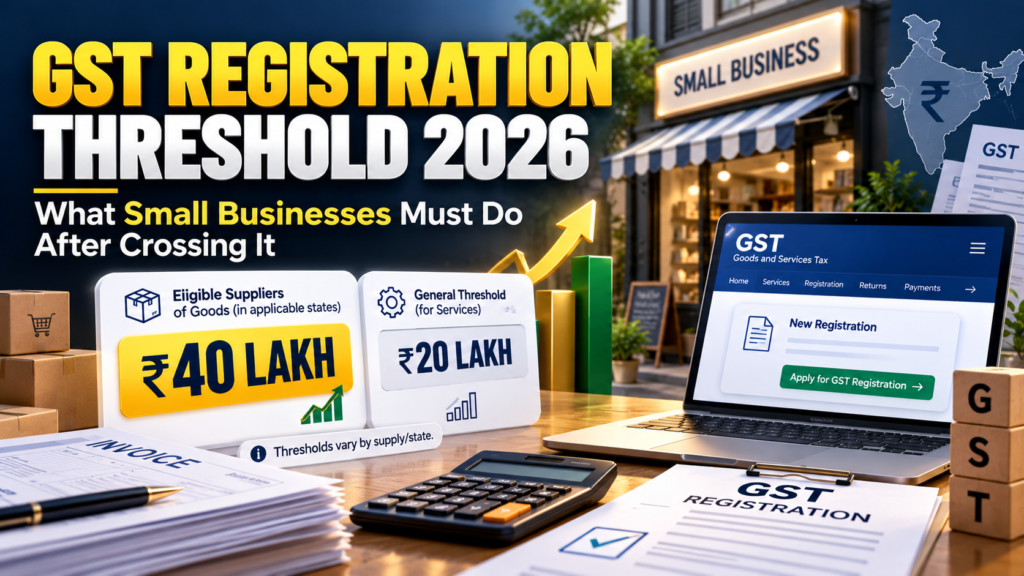
TL;DR Crossing the GST registration threshold can significantly change how a small business manages its sales, invoices, tax collection and accounting. For many businesses, the applicable threshold depends on whether they supply goods or services, the State or Union Territory in which they operate, and whether any compulsory-registration provision applies. CBIC’s current published guidance provides a threshold of ₹40 lakh for suppliers exclusively engaged in goods in eligible States, while the general threshold for services is ₹20 lakh, subject to lower thresholds in specified States and other exceptions. Once registration becomes applicable, the business may need to obtain a GSTIN, issue GST-compliant tax invoices, charge and report GST, file applicable returns, maintain records and manage Input Tax Credit. The important point is that businesses should track aggregate turnover continuously instead of waiting until year-end. What Is the GST Registration Threshold? GST registration is generally linked to a business’s aggregate turnover. Aggregate turnover is not simply the amount of taxable sales made by a business. Under the GST framework, it is calculated on an all-India basis for the same PAN and generally includes taxable supplies, exempt supplies, exports and inter-State supplies, while GST taxes themselves are excluded. Certain specified items, including inward supplies on which tax is payable under reverse charge, are excluded from aggregate turnover. The applicable threshold can vary depending on the nature of the business. For example, CBIC’s published guidance provides: ₹40 lakh threshold for suppliers exclusively supplying goods in States/UTs where the higher threshold applies ₹20 lakh threshold generally applicable to suppliers of services Lower thresholds in certain specified States Therefore, a business should not assume that the same turnover limit applies to every taxpayer. Why the Turnover Threshold Matters For a small business operating below the applicable threshold and not falling under compulsory-registration provisions, GST registration may not be mandatory. But once the business becomes liable for registration, its compliance responsibilities change. The business may need to: Apply for GST registration Obtain a GSTIN Issue tax invoices Charge applicable GST Maintain GST records File GST returns Reconcile sales Claim eligible Input Tax Credit Track GST payments Respond to GST notices, where applicable The GST Portal’s registration guidance states that the date on which registration liability arises must be entered in the registration application, and an application filed within 30 days can have registration effective from the date liability arose. What Counts Toward Aggregate Turnover? One of the most common mistakes is monitoring only taxable sales. Aggregate turnover can include: Taxable supplies Exempt supplies Export supplies Inter-State supplies Supplies made under the same PAN across India GST itself is excluded from the calculation. For example, suppose a business has: Type of Supply Annual Value Taxable sales ₹27 lakh Exempt supplies ₹5 lakh Export services ₹4 lakh Other qualifying supplies ₹3 lakh Aggregate turnover ₹39 lakh The business cannot simply look at the ₹27 lakh taxable-sales figure and conclude that its aggregate turnover is ₹27 lakh. The complete turnover position needs to be examined. The Same PAN Matters Aggregate turnover is generally considered on an all-India basis for the same PAN. This becomes particularly important where a business operates from multiple locations or has multiple registrations. For example, if the same PAN has business activities in Maharashtra and Gujarat, turnover from the relevant supplies is not simply evaluated independently as two unrelated businesses for determining aggregate turnover. CBIC’s GST guidance specifically explains that turnover across businesses under the same PAN is considered for the threshold. What Changes Once GST Registration Becomes Applicable? The transition from an unregistered business to a registered taxpayer is more than just obtaining a GST number. The business’s entire billing and accounting process may need to change. 1. GSTIN Becomes Part of Business Documentation After registration, the GSTIN becomes an important identifier for GST compliance. The business should ensure that the GSTIN and other required particulars appear correctly on applicable documents. 2. Tax Invoices Need to Be Issued A registered taxpayer generally needs to issue GST-compliant tax invoices for taxable supplies. The invoice should contain the information required under the applicable GST rules. This is different from the ordinary commercial invoice that an unregistered small business may use. 3. GST Needs to Be Accounted For Once the business becomes liable to pay GST, it must determine the applicable tax treatment of its supplies. Depending on the transaction, this can involve: CGST SGST/UTGST IGST Exempt supplies Zero-rated supplies Reverse-charge transactions The correct treatment depends on the nature and location of the supply. Does Crossing the Threshold Mean GST Applies to Every Receipt? Not necessarily. GST is based on supplies covered by the GST law, and the tax treatment can vary depending on the nature of each transaction. A business can have: Taxable supplies Exempt supplies Zero-rated supplies Non-GST supplies The registration threshold and GST liability should therefore be analysed using the applicable GST provisions rather than simply applying a fixed percentage to every bank credit. What Happens to Input Tax Credit? One of the major changes after GST registration is the potential availability of Input Tax Credit (ITC), subject to the statutory conditions and restrictions. For example, a registered business may incur GST on: Raw materials Business purchases Professional services Rent Software Office expenses Other eligible inputs and input services Where the relevant legal conditions are satisfied, eligible GST paid on business inputs can potentially be claimed as ITC. However, registration does not mean that every GST amount paid automatically becomes ITC. Businesses should verify: Valid tax invoice Supplier details Receipt of goods/services Eligibility of the expense Return/reporting requirements Applicable restrictions GST Returns Become Part of Regular Compliance Once registered, the business enters the GST return-filing system. For normal taxpayers, GSTR-1 is used to report details of outward supplies. The GST Portal states that normal and casual registered taxpayers making outward supplies generally file GSTR-1, subject to applicable exclusions such as composition taxpayers. Depending on the taxpayer’s circumstances and filing option, returns may be monthly or quarterly. This means GST compliance becomes an
New Income Tax Rules 2026: What Businesses, Professionals and Taxpayers Need to Review Now
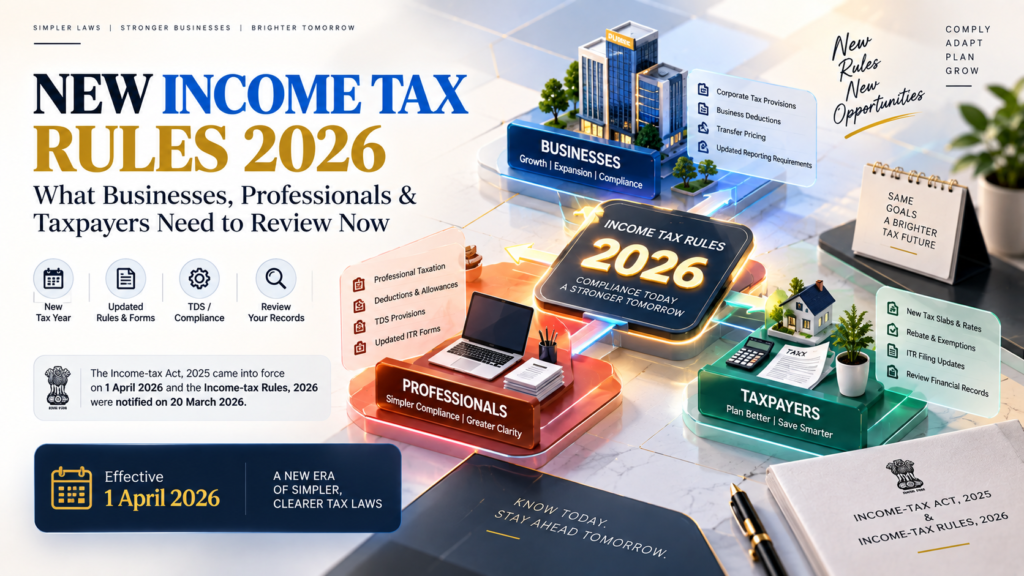
TL;DR 2026 is an important transition year for India’s income-tax system. The Income-tax Act, 2025 came into force from 1 April 2026, replacing the Income-tax Act, 1961 for the new tax framework. This means businesses, professionals and individual taxpayers need to understand more than just changes in tax rates. They also need to review their accounting systems, tax records, TDS processes, return filing procedures, notices, documentation and compliance workflows. The new framework also introduces changes in terminology and the structure of tax provisions. For taxpayers, the practical objective should be to identify which rules apply to the relevant tax year, update internal processes and avoid continuing with outdated assumptions from the earlier law. Why 2026 Is Different for Income-Tax Compliance The biggest change is the transition from the Income-tax Act, 1961 to the Income-tax Act, 2025. The new Act came into force on 1 April 2026. This creates an important distinction between tax periods. For income relating to the financial year ending 31 March 2026, taxpayers generally continue dealing with the earlier framework applicable to that period. For income earned from 1 April 2026 onward, the new Income-tax Act, 2025 becomes relevant. This means businesses should not treat all 2026 tax matters as if they fall under one set of provisions. Tax Year vs Earlier Assessment-Year Terminology One of the changes taxpayers need to understand is the shift toward the concept of a Tax Year. Under the new framework, the tax year generally corresponds to the financial year in which income is earned. For example: 1 April 2026 – 31 March 2027 = Tax Year 2026–27 This is different from the familiar earlier terminology where income earned during a financial year was generally assessed in the following assessment year. Businesses should therefore review the terminology used in: Accounting software Tax reports Internal MIS Tax invoices and documentation where relevant TDS systems Return-filing processes Tax notices and correspondence Professional tax workpapers Businesses Need to Review Their Accounting Systems The transition to the new Act makes accounting-system review particularly important. Businesses should check whether their accounting and tax software is updated for the new framework. Important areas include: Tax calculation TDS Advance tax Tax depreciation Deductions Tax return preparation Tax audit reporting Employee taxation Tax notices Financial reporting An outdated system can create errors even when the underlying accounting records are correct. Review Your Tax Calculation Method Businesses and professionals should review how tax liability is being calculated under the new framework. Tax calculation should consider: Applicable tax rates Tax regime Deductions Exemptions Business income Capital gains Other income TDS credits Advance tax Tax payments Applicable surcharge and cess Taxpayers should avoid relying on calculators or spreadsheets prepared under the previous law without verifying whether the underlying provisions are still applicable. Businesses Should Review Their TDS Process TDS is one of the areas where incorrect implementation can create recurring compliance problems. Businesses should review: TDS sections Applicable rates Deduction timing Payment timelines TDS returns Certificates PAN details Vendor classification Employee TDS Contractor payments Professional fees Rent Interest payments The accounting team should ensure that the TDS configuration in accounting or payroll software reflects the provisions applicable from the relevant tax year. Employee Payroll Also Needs Attention Companies should review their payroll systems after the transition to the new income-tax framework. Payroll teams should verify: Employee declarations Tax regime selection Salary components Perquisites Allowances Deductions TDS calculations Form 16 data Taxable benefits Employees should also review their salary structure and tax declarations instead of assuming that previous-year calculations automatically remain valid. Professionals Should Review Presumptive Taxation Professionals operating as independent consultants, freelancers or eligible professionals should review the provisions applicable to their income. Areas that may require attention include: Professional receipts Business expenses Books of account Presumptive taxation Tax audit applicability Advance tax TDS credits Return filing Professionals should not automatically carry forward the previous year’s tax treatment without checking the provisions applicable to the new tax year. Businesses Should Review Tax-Deductible Expenses Companies should review whether their expense classification and supporting documentation are adequate. Important areas include: Employee expenses Professional fees Interest Repairs Travel Advertising Business promotion Rent Depreciation Donations Related-party payments Statutory payments The accounting team should maintain proper supporting documentation for significant expenses. A tax deduction should not be assumed simply because an expense appears in the profit and loss account. Capital Gains Reporting Should Be Reviewed Individuals and businesses with investments should pay attention to the tax treatment of capital gains under the new framework. Taxpayers should maintain records for: Purchase date Purchase cost Sale date Sale consideration Expenses Securities transactions Property transactions Capital improvements TDS, where applicable Investment-related tax calculations should be based on the provisions applicable to the relevant tax year. AIS and TIS Still Matter Taxpayers should continue reviewing information appearing in their Annual Information Statement (AIS) and Taxpayer Information Summary (TIS). These records can contain information relating to: Interest income Dividend income Securities transactions Property transactions TDS TCS Other reported financial transactions A mismatch between AIS/TIS and the taxpayer’s own records should be investigated before filing the relevant return. Taxpayers should not automatically assume that every AIS entry is correct. Advance Tax Planning Becomes More Important Businesses and professionals should estimate tax liability during the year rather than waiting until year-end. Advance tax planning should consider: Current-year profits Capital gains Interest income Dividend income TDS already deducted Previous tax payments Expected deductions Business changes Regular tax projections can help identify underpayment before interest consequences arise. Review Your Tax Documents Businesses and professionals should maintain a structured tax-documentation system. Important records can include: Sales invoices Purchase invoices Expense bills Bank statements Investment statements Loan documents TDS certificates GST records Payroll records Property documents Capital asset records Previous tax returns Tax notices Audit reports Digital record-keeping can make future tax assessments and notices easier to manage. GST and Income-Tax Data Should Also Be Reconciled Businesses should not treat GST and income-tax compliance as completely separate systems. Differences can occur between: Books → GST returns → TDS