Depreciation Rates FY 2025-26 – Income Tax Act
Introduction Depreciation is a critical concept in taxation and accounting. Under Section 32 of the Income Tax Act, 1961, depreciation allows taxpayers to claim a deduction for the gradual wear and tear of tangible and intangible assets used in business or profession. It ensures that the cost of assets is spread across their useful life, aligning tax deductions with economic reality.For FY 2025-26, depreciation continues to be calculated either on the Written Down Value (WDV) method or the Straight Line Method (SLM). The Income Tax Act prescribes specific rates for different blocks of assets, ensuring uniformity and fairness in tax computation Depreciation Rates (WDV Method) The WDV method is the default method applicable to most businesses. Assets are grouped into blocks, and depreciation is applied to the block as a whole rather than individual assets. Below is the detailed chart: Sr No Particulars of Asset Rate of Depreciation 1 Buildings used mainly for residential purposes (except hotels & boarding houses) 5% 2 Buildings other than residential (including offices, factories, godowns, hotels) 10% 3 Purely temporary erections such as wooden structures 40% 4 Furniture & fittings including electrical fittings 10% 5 Plant & machinery (general) 15% 6 Motor cars (not used for hire) 15% 7 Motor cars, other than those used in a business of running them on hire, acquired on or after the 23rd day of August, 2019 but before the 1st day of April, 2020 and is put to use before the 1st day of April, 2020. 30% 8 Motor buses, lorries, taxis used for hire 30% 9 Motor buses, motor lorries and motor taxis used in a business of running them on hire, acquired on or after the 23rd day of August, 2019 but before the 1st day of April, 2020 and is put to use before the 1st day of April, 2020. 45% 10 Aeroplanes, aero engines 40% 11 Ships 20% 12 Computers including software 40% 13 Life saving medical equipment 40% 14 Energy saving devices 40% 15 Books (annual publications) 100% 16 Books (other than annual publications) 60% 17 Gas cylinders, containers 40% 18 Rolling mills, steel plant machinery 40% 19 Intangible assets (goodwill, patents, trademarks, licenses, franchises, know-how) 25% Notes (WDV Method) • Depreciation is calculated on the block of assets, not individual items. • If an asset is acquired and put to use for less than 180 days in the year, only 50% of the rate is allowed. • Additional depreciation of 20% is available for new plant and machinery acquired by manufacturing undertakings. • Certain specialized assets (like books, gas cylinders, rolling mills) enjoy higher rates due to faster wear and tear. ________________________________________ Depreciation Rates (SLM Method) The Straight Line Method is applicable primarily to undertakings engaged in generation or distribution of power. Instead of fixed rates, assets are depreciated based on their useful life. distribution of power. Instead of fixed rates, assets are depreciated based on their useful life. Sr No Particulars of Asset Life of Asset (Years) 1 Buildings (RCC Frame Structure, other than factory buildings) 60 2 Buildings (other than RCC Frame Structure, including factory buildings) 30 3 Fences, wells, tube wells 5 4 Temporary structures, others 3 5 Bridges, culverts, bunders 30 6 Carpeted Roads – RCC 10 7 Carpeted Roads – other than RCC 5 8 Non-carpeted Roads 3 9 Plant & Machinery (general) 15 10 Continuous process plant (not covered under special industries) 25 11 Cinematograph film machinery & projecting equipment 13 12 Glass manufacturing – furnaces 13 13 Glass manufacturing – moulds 8 14 Float glass melting furnaces 10 15 Mines & quarries – portable machinery 8 16 Telecom towers 18 17 Telecom equipment (switching, transmission, etc.) 13 18 Telecom ducts, cables, optical fibre, satellites 18 19 Oil & gas – refineries, assets, petrochemical plant, storage tanks, drilling rigs 25 20 Oil & gas – pipelines 30 21 Oil & gas – field operations equipment, loggers 8 22 Power generation – Thermal, Hydro, Nuclear, Transmission lines 40 23 Wind Power Plant 22 24 Electric Distribution Plant 35 25 Gas Storage & Distribution Plant, Water Distribution Plant 30 26 Steel – Sinter Plant, Blast Furnace, Coke Ovens, Rolling Mill 20 27 Steel – Basic Oxygen Furnace Converter 25 28 Non-ferrous metals – major equipment (pot line, digester, turbine, calcination, copper smelter, roll grinder) 40 29 Non-ferrous metals – Soaking Pit, Annealing Furnace, Rolling Mills, Scalping/Slitting equipment 30 30 Non-ferrous metals – Surface Miner, Ripper Dozer, Copper refining plant 25 31 Medical diagnostic equipment (X-ray, ECG, Ultrasound, etc.) 13 32 Other medical equipment 15 33 Pharmaceuticals – reactors, distillation, drying, tanks 20 34 Civil construction – concreting, crushing, piling, road making 12 35 Civil construction – cranes >100 tons 20 36 Civil construction – cranes <100 tons 15 37 Civil construction – transmission line, tunneling equipment 10 38 Civil construction – earth-moving equipment 9 39 Civil construction – other construction equipment 12 40 Salt works machinery 15 41 Furniture & fittings (general) 10 42 Furniture in hotels, restaurants, schools, theatres, etc. 8 43 Motor cycles, scooters, mopeds 10 44 Motor buses, lorries, cars, taxis (used for hire) 6 45 Motor buses, lorries, cars (not used for hire), tractors, harvesters, heavy vehicles, electric vehicles 8 46 Ocean-going ships – bulk carriers, liners, passenger vessels, coastal ships 25–30 47 Crude/product/chemical tankers 20–25 48 Offshore supply/support vessels, catamarans, high-speed boats 20 49 Drill ships 25 50 Hovercrafts 15 51 Fishing vessels (wooden hull) 10 52 Dredgers, tugs, barges, survey launches 14 53 Inland water vessels – speed boats 13 54 Inland water vessels – others 28 55 Aircrafts & helicopters 20 56 Railways sidings, locomotives, rolling stock, tramways 15 57 Ropeway structures 15 58 Office equipment 5 59 Computers – servers & networks 6 60 Computers – desktops, laptops 3 61 Laboratory equipment (general) 10 62 Laboratory equipment (educational institutions) 5 63 Electrical installations & equipment 10 64 Hydraulic works, pipelines, sluices 15 Key Notes • Blocks with identical useful lives have been combined for clarity (e.g.,
TDS Rates FY 2026-27 – Complete Guide

Introduction Tax Deducted at Source (TDS) is a vital compliance mechanism under the Income Tax Act, ensuring tax collection at the point of income generation. For FY 2026-27, the Income Tax Department has notified updated rates applicable to residents and non-residents. While the overall framework remains consistent with FY 2025-26, there are important clarifications and changes that taxpayers must note. TDS on Payments to Residents- FY 2026-27 Sl. No. Nature of Income Payer Rate Threshold Limit 1. Commission or brokerage (i) Insurance commission Any person Rates in force ₹20,000 (ii) Other commission/brokerage Specified person 2% ₹20,000 2. Rent (i) Rent – person other than specified person Any person 2% ₹50,000 per month (ii) Rent – specified person Specified person 2% (machinery/plant), 10% (land/building/furniture) ₹50,000 per month 3. Transfer of immovable property (other than agricultural land) (i) Consideration for transfer Any person 1% of consideration or stamp duty value ₹50 lakh (ii) Agreement under section 67(14) Any person 10% Nil (iii) Compensation/enhanced consideration on compulsory acquisition Any person 10% ₹5,00,000 4. Income from capital market (i) Mutual fund units, specified company units Any person 10% ₹10,000 (ii) Distributed income – business trust Business trust 10% Nil (iii) Units of investment fund Investment fund 10% Nil (iv) Securitisation trust income Securitisation trust 10% Nil 5. Interest income (i) Interest on securities Any person Rates in force ₹10,000 (ii) Interest (banks, co-op banks, post office) Banking company/co-op/post office Rates in force ₹50,000 (others), ₹1,00,000 (senior citizens) (iii) Other interest Specified person Rates in force ₹10,000 6. Contractors / Professional fees (i) Work contracts Designated person 1% (individual/HUF), 2% (others) ₹30,000 single, ₹1,00,000 aggregate (ii) Work/professional fees/commission Individual/HUF 2% ₹50 lakh (iii) Professional/technical fees, royalty, director remuneration Specified person 2%–10% ₹50,000 (most cases), Nil (director fees) 7. Dividend Dividend declared Domestic company 10% Nil 8. Other cases (i) Life insurance payout Any person 2% ₹1,00,000 (ii) Purchase of goods > ₹50 lakh Buyer 0.1% Above ₹50 lakh (iii) Senior citizen income (bank deduction) Specified bank Rates in force As applicable (iv) Business/professional perquisites Specified person 10% ₹20,000 (v) E-commerce transactions E-commerce operator 0.1% Nil (vi) Transfer of virtual digital assets Any person 1% Nil TDS on Payments to Non-Residents FY 2026-27 Sl. No. Nature of Income Payee Payer Rate 1 Income of non-resident sportsman/entertainer Non-resident Any person 20% 2 Interest on foreign currency loans/bonds (pre-2023 issues) Non-resident / foreign company Indian company / trust 5% 3 Interest on rupee denominated bonds (pre-2023) Non-resident / foreign company Indian company / trust 5% 4 Interest on IFSC listed bonds Non-resident / foreign company Indian company / trust 4% (till June 2023), 9% (after July 2023) 5 Interest from infrastructure debt fund Non-resident / foreign company Debt fund 5% 6 Distributed income from business trust Non-resident unit holder Business trust 5%–10% 7 Other distributed income from business trust Non-resident unit holder Business trust Rates in force 8 Units of investment fund Non-resident unit holder Investment fund Rates in force 9 Securitisation trust income Non-resident investor Trust Rates in force 10 Mutual fund units / specified company units Non-resident Any person 20% (subject to DTAA) 11 Offshore fund units Offshore fund Any person 10% 12 LTCG on offshore fund units Offshore fund Any person 12.5% 13 Interest/dividends on GDRs/bonds Non-resident Any person 10% 14 LTCG on GDRs/bonds Non-resident Any person 12.5% 15 Securities income (FII) FII Any person 20% (subject to DTAA) 16 Securities income (specified fund) Specified fund Any person 10% 17 Other interest/sums (not salaries) Non-resident / foreign company Any person Rates in force Key Changes Compared to FY 2025-26 Commission & Brokerage: Insurance commission moved from flat 2% (FY 2025-26) to “rates in force” in FY 2026-27, tightening compliance. Rent: No rate change, but clearer distinction between specified persons and others. Immovable Property Transfers: Clarification that threshold applies to aggregate consideration/stamp duty value, reducing disputes. Capital Market Income: Expanded coverage to include securitisation trust income at 10%. Interest Income: Shift from fixed 10% to “rates in force,” aligning with slab-based taxation. Contractors & Professional Fees: More granular categorization; call centres taxed at concessional 2%. Dividends: Threshold exemption of ₹10,000 removed; now all dividends taxable at source. Other Cases: Purchase of Goods: Deduction only on excess above ₹50 lakh clarified. E-commerce: Threshold removed; 0.1% applies from the first rupee. Virtual Digital Assets (VDAs): Threshold removed; 1% applies universally, stricter compliance. Senior Citizens: Banks deduct directly after considering deductions/rebates, simplifying compliance. Non-Resident Payments: IFSC bond rate clarified — 4% till June 2023, 9% thereafter. Conclusion The FY 2026-27 TDS framework builds on FY 2025-26 but introduces stricter compliance for dividends, VDAs, and e-commerce transactions, rationalizes insurance commission and interest income to “rates in force,” and expands coverage to securitisation trusts. Threshold exemptions have been reduced, making TDS more comprehensive and aligned with evolving digital and financial transactions. For TDS on payments to a non-resident or NRI tax planning, see our NRI and expatriate taxation services in Pune. BLOG BY – MITTAL & CO.
GSTN Advisory: Key Enhancements in GSTR-3B Filing Effective from February 2026 Tax Period
Introduction The Goods and Services Tax Network (GSTN) had earlier announced that several important enhancements in the filing of GSTR-3B returns would take effect from the January 2026 tax period. However, it has now been clarified that these changes will be implemented starting from the February 2026 tax period. The enhancements are aimed at simplifying compliance, improving accuracy in interest computation, and providing taxpayers with better clarity in reporting. By introducing system-driven features and aligning them with statutory provisions under the CGST Act, 2017, the GSTN seeks to reduce disputes, enhance transparency, and empower taxpayers to manage their obligations more efficiently. Update in Interest Computation – Table 5.1 Interest liability has long been a sensitive issue for taxpayers, particularly when returns are filed late. The new enhancement provides a more equitable and system-driven approach to interest calculation. Revised Formula Key Features System-driven computation: Interest will now be auto-populated in Table 5.1 of GSTR-3B using the revised formula. Non-reducible values: Taxpayers cannot reduce the auto-populated interest amount. However, they may increase it if their self-assessment shows a higher liability. Relief through cash balance: The formula considers the minimum cash balance available in the Electronic Cash Ledger (ECL) between the due date of return filing and the date of tax payment (offset). This reduces unnecessary interest burden. Applicability: The enhancement applies to delayed returns filed for January 2026, but the interest will be auto-populated in the February 2026 GSTR-3B. This update ensures alignment with Rule 88B(1) of the CGST Rules, 2017, thereby providing fairness and consistency in interest computation. Auto-Population of Tax Liability Breakup Table Late reporting of invoices often leads to mismatches between GSTR-1 and GSTR-3B. To address this, the GST portal now introduces auto-population of the Tax Liability Breakup Table. How It Works Captures supplies of previous tax periods that are reported in the current period. Auto-populated based on the date of documents reported in GSTR-1 / GSTR-1A / IFF. Ensures accurate linkage between tax liability and the period of supply. Benefits Accuracy: Reduces manual errors in reporting liabilities. Transparency: Provides a clear breakup of liability, making reconciliation easier. Ease of access: Taxpayers can view the breakup at: Login → GSTR-3B Dashboard → Table 6.1 (Payment of Tax) → Tax Liability Breakup. This enhancement strengthens reconciliation processes and ensures taxpayers report liabilities correctly, especially when invoices are reported late. Cross-Utilization of ITC – Table 6.1 Input Tax Credit (ITC) utilization has been simplified with a new flexibility feature in Table 6.1 of GSTR-3B. Key Change Once IGST ITC is fully exhausted, taxpayers can now pay IGST liability using CGST and SGST ITC in any sequence. Implications Flexibility: Removes rigid rules of ITC utilization, giving taxpayers more control. Efficiency: Helps in optimal use of available credits, reducing cash outflow. Simplification: Eliminates confusion around the sequence of utilization, making compliance smoother. This change is particularly beneficial for businesses engaged in interstate transactions, where IGST liability is common and efficient credit utilization is critical. Collection of Interest in GSTR-10 Compliance obligations continue even after cancellation of GST registration. The new enhancement ensures accountability in such cases. Key Change If the last applicable GSTR-3B return is filed late, the interest liability will be collected through GSTR-10 (Final Return). Benefits Closure of compliance: Ensures obligations are met even post-cancellation. Revenue protection: Prevents leakage by capturing interest liability at the time of final return filing. Clarity: Provides a clear mechanism for cancelled taxpayers to settle outstanding liabilities. This ensures that compliance obligations are fulfilled until the final return is filed, reinforcing accountability. Crux of the Enhancements To summarize, here are the four core changes taxpayers must note, now applicable from the February 2026 tax period: Interest Computation Update: Auto-populated, system-driven interest in Table 5.1, considering ECL balance. Tax Liability Breakup Table: Auto-populated linkage of past supplies with current tax payments. Cross-Utilization of ITC: Flexibility to use CGST and SGST ITC for IGST liability once IGST ITC is exhausted. Interest Collection in GSTR-10: Late filing interest captured in the final return for cancelled taxpayers. Conclusion The enhancements in GSTR-3B filing, now effective from the February 2026 tax period, represent a significant step toward simplifying GST compliance. By introducing system-driven interest computation, auto-populated tax liability tables, flexible ITC utilization, and streamlined interest collection in GSTR-10, the GSTN has reinforced its commitment to accuracy and transparency. While these changes reduce manual intervention and errors, taxpayers must continue to self-assess and verify their records to ensure compliance with statutory provisions. Ultimately, these updates align the GST framework more closely with the legal requirements under the CGST Act and Rules, fostering trust, efficiency, and confidence in India’s tax ecosystem. For GSTR-3B filing and GST registration support, see our GST registration and return filing services in Pune. BLOY BY – MITTAL & CO.
Advance Tax Calculation FY 2025-26 (AY 2026-27) – Things to Remember!
Introduction Advance tax is one of the most important compliance requirements under the Income Tax Act. It ensures that taxpayers pay their dues in instalments as income is earned, rather than waiting until the end of the financial year. This “pay-as-you-earn” system prevents a heavy burden at year-end and helps the government maintain steady revenue inflows. For Financial Year (FY) 2025-26, corresponding to Assessment Year (AY) 2026-27, advance tax assumes greater importance because of the new slab rates and enhanced rebate limits. Whether you are a salaried employee, a professional, or a business owner, understanding these changes is crucial to avoid interest liability and manage cash flow effectively. AY 2026-27 – Key Changes to Remember New Income Tax Slabs under Section 115BAC The new regime slab rates have been revised as follows: Income Range Tax Rate 0 – 4 Lakhs Nil 4 – 8 Lakhs 5% 8 – 12 Lakhs 10% 12 – 16 Lakhs 15% 16 – 20 Lakhs 20% 20 – 24 Lakhs 25% Above 24 Lakhs 30% Enhanced Section 87A Rebate The rebate threshold under the new regime has been increased from ₹7,00,000 to ₹12,00,000. Taxpayers with income up to ₹12 lakh (excluding special rate incomes like capital gains) can effectively pay zero tax. Marginal relief is available for those slightly above ₹12 lakh. Points to Remember While Paying Advance Tax Who Needs to Pay? Any taxpayer with tax liability exceeding ₹10,000 in a financial year. Applies to individuals, firms, companies, and professionals. Senior citizens (60+) without business income are exempt. Instalment Schedule Advance tax is payable in four instalments: 15% by 15th June 2025 45% by 15th September 2025 75% by 15th December 2025 100% by 15th March 2026 For presumptive taxpayers under Sections 44AD/44ADA, the entire liability is payable by 15th March 2026. Estimate Income Carefully Include all sources: Salary (including bonuses and incentives) Business/professional income Rental income Capital gains Interest/dividends 👉 Additional Note: If you have switched jobs during the year, ensure that salary from your previous employer is also considered in your advance tax calculation. If not disclosed to the current employer, this income may be missed in TDS computation, leading to shortfall and interest liability. Adjust for TDS/TCS Deduct taxes already withheld at source to avoid double payment. With revised thresholds, fewer deductions may occur, so advance tax liability could rise. Capital Gains & Windfall Income If capital gains or windfall income (lottery, horse race winnings) arise mid-year, pay advance tax in the next instalment to avoid interest under Section 234C. 👉 Additional Note: Capital gains tax should be calculated considering the new slab rates and applicable surcharge. Ensure you apply the correct rate for short-term and long-term gains, as these are taxed differently from regular income. Housing Loan Interest Deduction Obtain a provisional interest certificate from your bank for housing loan deductions. Compare it with actual payments made during the year to ensure accuracy in claiming deductions under Section 24(b). Choice of Tax Regime Taxpayers with business income must choose their regime (old vs. new) wisely. Once opted, switching is restricted under law. Check eligibility before making the choice, as this impacts advance tax liability significantly. Surcharge Rates Verify applicable surcharge rates carefully, especially for high-income taxpayers. Misapplication can lead to underpayment and subsequent interest. Corporate Taxpayers – MAT Companies must also check Minimum Alternate Tax (MAT) calculations to ensure compliance. Advance tax liability should be computed considering both normal provisions and MAT, whichever is higher. Brought Forward Loss Adjustment Before finalizing advance tax, adjust for brought forward business losses, depreciation, and capital losses. This reduces taxable income and prevents excess payment. Practical Tips for Smooth Compliance Quarterly Review: Reassess income projections every quarter. Use Online Calculators: Simplify estimation with official calculators. Plan Cash Flow: Align payments with inflows to avoid liquidity crunch. Professional Guidance: Seek advice for complex income streams. Stay Updated: Monitor CBDT notifications and Budget changes. Conclusion Advance tax is not just a compliance requirement—it’s a proactive financial discipline. For FY 2025-26 (AY 2026-27), taxpayers must pay close attention to the new slab rates, enhanced rebate limits, revised TDS thresholds, and extended updated return timelines. By estimating income carefully, including salary from previous employers, considering capital gains under new rates, checking housing loan deductions, and applying surcharge/MAT provisions correctly, you can avoid penalties and maintain peace of mind. Advance tax spreads your liability across the year, ensures compliance, and reflects responsible financial planning. In short, timely advance tax payments save you from unnecessary interest, penalties, and stress—while keeping you firmly on the right side of the law. BLOG BY – MITTAL & CO.
GST Update: Withdrawal from Rule 14A from 21 Feb 2026
Introduction On February 21, 2026, GSTN rolled out a new online facility allowing taxpayers to withdraw from the option availed under Rule 14A of the CGST Rules. This is a significant compliance update, as it provides clarity and a structured process for opting out through the filing of Form GST REG-32 on the GST Portal. Let’s break down the key updates, applicability, and timelines. What is Rule 14A of CGST Rules? Rule 14A of the CGST Rules is a simplified compliance scheme introduced to encourage voluntary participation by small businesses and service providers with minimal tax liability. It allows eligible taxpayers to obtain automatic electronic GST registration within three days of submitting FORM GST REG-01, provided they select “Yes” for Rule 14A during application. The scheme mandates Aadhaar authentication for the Primary Authorised Signatory and at least one Promoter or Partner, ensuring transparency and identity verification. To maintain its focus on genuinely small taxpayers, Rule 14A restricts multiple registrations under the same PAN within a State or Union Territory and applies only to those whose monthly output tax liability on supplies to registered persons does not exceed ₹2.5 lakh. In essence, Rule 14A offers a faster, paperless, and more secure registration pathway tailored for small-scale taxpayers. Key Updates introduced on 21st February, 2026 New Online Facility for withdrawal from 14A: Taxpayers registered under can now apply for withdrawal directly on the GST Portal. Eligible Taxpayers: Only active taxpayers registered under Rule 14A can apply for withdrawal. Form GST REG-32: This form is the prescribed application for opting out. Aadhaar Authentication: Mandatory for the Primary Authorised Signatory and at least one Promoter/Partner. Authentication can be OTP-based or biometric. Timelines: Draft application must be submitted within 15 days of creation. Aadhaar/Biometric authentication must be completed within 15 days of submission. ARN will only be generated after successful authentication. Restrictions During Processing: While the application is pending, taxpayers cannot file core/non-core amendments or self-cancellation requests. Post-Sanction Compliance: Once withdrawal is approved via Form GST REG-33, taxpayers must furnish details of output tax liability exceeding ₹2.5 lakhs from the first day of the succeeding month. Pre-conditions for Filing Form GST REG-32: Returns for at least three months must be filed if applying before April 1, 2026. Returns for at least one tax period must be filed if applying on or after April 1, 2026. All returns due from the effective date of registration till the date of filing must be furnished. How to Apply on GST Portal Login to the GST Portal. Navigate to: Services → Registration → Application for Withdrawal from Rule 14A. The link will be visible only if the taxpayer is active and registered under Rule 14A. The field “Option for registration under Rule 14A” will be auto-selected as No. Enter the reason for withdrawal. Complete Aadhaar Authentication for the Primary Authorised Signatory and one Promoter/Partner. Submit the application and ensure authentication is completed within the prescribed timeline. Conclusion The introduction of Form GST REG-32 for withdrawal from Rule 14A marks a step towards streamlined compliance and transparency. Taxpayers now have a clear digital pathway to opt out, backed by Aadhaar authentication and defined timelines. However, it is crucial to ensure that all returns are filed and authentication is completed promptly to avoid rejection or delays. This facility empowers taxpayers with flexibility while reinforcing accountability in GST compliance. BLOG BY – MITTAL & CO.
Income Tax & Surcharge Rates for FY 2025-26 (AY 2026-27)
Income Tax & Surcharge Rates for FY 2025-26 (AY 2026-27) Income tax planning requires a clear understanding of applicable tax rates, surcharge slabs, and rebates. For FY 2025-26 (AY 2026-27), taxpayers can choose between the old regime with exemptions and deductions, or the new regime with simplified slabs and higher exemption limits. Below is a comprehensive guide to tax rates for individuals, firms, LLPs, and companies, along with surcharge applicability and rebates. Tax Rates for Individuals, HUFs, AOPs, BOIs Old Regime The taxpayer has to exercise the option under section 115BAC(6) to avail the benefit of old tax regime. The normal tax rates applicable to a resident individual will depend on the age of the individual. However, in case of a non-resident individual the tax rates will be same irrespective of his age. For the purpose of ascertainment of the applicable tax slab, an individual can be classified as follows: Resident individual below the age of 60 years Resident individual of the age of 60 years or above at any time during the year but below the age of 80 years Resident individual of the age of 80 years or above at any time during the year Non-resident individual irrespective of the age. Category Income Range Tax Rate Individuals (<60 years) & Non-residents Up to ₹2,50,000 Nil ₹2,50,001 – ₹5,00,000 5% ₹5,00,001 – ₹10,00,000 20% Above ₹10,00,000 30% Senior Citizens (60–79 years) Up to ₹3,00,000 Nil ₹3,00,001 – ₹5,00,000 5% ₹5,00,001 – ₹10,00,000 20% Above ₹10,00,000 30% Super Senior Citizens (80+ years) Up to ₹5,00,000 Nil ₹5,00,001 – ₹10,00,000 20% Above ₹10,00,000 30% New Regime u/s 115BAC (Default) Income Range Tax Rate Up to ₹4,00,000 Nil ₹4,00,001 – ₹8,00,000 5% ₹8,00,001 – ₹12,00,000 10% ₹12,00,001 – ₹16,00,000 15% ₹16,00,001 – ₹20,00,000 20% ₹20,00,001 – ₹24,00,000 25% Above ₹24,00,000 30% Rebate under Section 87A Old Regime: Rebate up to ₹12,500 if income ≤ ₹5,00,000. New Regime (AY 2026-27): Rebate up to ₹60,000 if income ≤ ₹12,00,000, with marginal relief if income slightly exceeds ₹12,00,000. Surcharge Rates for Individuals Total Income Range Old Regime Surcharge New Regime Surcharge ₹50 lakh – ₹1 crore 10% 10% ₹1 crore – ₹2 crore 15% 15% ₹2 crore – ₹5 crore 25% 25% Above ₹5 crore 37% 25% Notes: Maximum surcharge on dividend income and capital gains under sections 111A, 112, 112A, and 115AD is capped at 15%. Marginal relief is available at each threshold to prevent excessive tax burden. Health & Education Cess 4% on income tax plus surcharge. Tax Rates for Firms & LLPs Entity Tax Rate Surcharge Cess Partnership Firm / LLP 30% 12% if income > ₹1 crore 4% on tax + surcharge Tax Rates for Companies Domestic Companies Category Tax Rate Surcharge Rate Health & Education Cess Turnover ≤ ₹400 crore (FY 2023-24) 25% 7% if income > ₹1 crore but upto ₹ 10 crores 12% if income > ₹10 crores 4% on tax + surcharge Other domestic companies 30% 7% if income > ₹1 crore but upto ₹ 10 crores 12% if income > ₹10 crores 4% on tax + surcharge Special Tax Regimes Section Tax Rate Surcharge Health & Education Cess 115BA 25% Income 1CR to 10 CR- 7% Income above 10 CR- 12% 4% on tax + surcharge 115BAA 22% Flat 10% 4% on tax + surcharge 115BAB 15% Flat 10% 4% on tax + surcharge Foreign Companies Category Tax Rate Surcharge Health & Education Cess All foreign companies 35% Income 1CR to 10 CR- 2% Income above 10 CR- 5% 4% on tax + surcharge Tax Planning Tips – AY 2026-27 Compare old vs. new regime before filing to choose the most tax-efficient option. Maximize deductions under 80C, 80D, and housing loan interest if opting for the old regime. Time capital gains to benefit from lower tax rates. Ensure advance tax payments are made on time to avoid interest under sections 234B/234C. Verify Form 26AS and AIS for TDS credits to prevent mismatches at filing. Companies can evaluate concessional regimes under sections 115BAA (22%) or 115BAB (15%). Maintain proper documentation for deductions, exemptions, and investments to ensure smooth compliance. Conclusion For AY 2026-27, the new regime is the default option, offering higher exemption limits and a generous rebate under section 87A. The old regime continues to benefit taxpayers who claim deductions and exemptions. Firms and companies face flat tax rates with surcharges based on income thresholds. BLOG BY – MITTAL & CO.
Income Tax Act 2026: Complete Form Number Changes

Introduction: The transition from the Income Tax Act, 1961 to the Income Tax Act, 2026 has brought significant structural and procedural changes, including comprehensive renumbering, consolidation, and rationalisation of statutory forms. While the core compliance framework such as audit reports, TDS/TCS statements, certificates, declarations, and applications continues in substance, the form numbers and corresponding section references have undergone substantial revision. Tax professionals, deductors, collectors, non-profit organisations, reporting entities, and other stakeholders must carefully align their compliance systems, documentation, and reporting processes with the new form numbers applicable from 2026 onwards. A clear understanding of these changes is essential to ensure accurate filings, avoid procedural defects, and maintain seamless compliance under the new regime. Frequently Used Forms: Form No. (1962) Form No. (2026) Description Section of Act/Rule 3CA,3CB,3CD 26 Audit report and Statement of particulars Section 63 3CEA 28 Report of an accountant relating to computation of capital gains in slump sale Section 77(4) 10BA 31 Declaration for deduction for rents paid Section 134 3CEB 48 Report from an accountant relating to international transaction(s) and specified domestic transaction(s) Section 172 29B 66 Computation of Book Profit Section 206(1) 29C 67 Report for Computation of Adjusted Total Income and Alternate Minimum Tax Section 206(2) 12BA 123 Statement showing particulars of perquisites, fringe benefits, amenities, profits in lieu of salary – 12BB 124 Statement showing particulars of claims by employee for deduction of tax Section 392(5)(b) 16A 131 Certificate for tax deducted at source Section 395(4) 16B,16C,16D,16E 132 Certificate for tax deducted at source Section 395(4) 49B(1) 134 Application for allotment of TAN (Government Entity) Section 397 49B(2) 135 Application for allotment of TAN (Other Entities) Section 397 24Q 138 Quarterly statement of deduction of tax on salary/senior citizen income Sections 392 26Q 140 Quarterly statement of deduction of tax on payments other than salary Section 397(3)(b) 26QB,26QC,26QD,26QE 141 Challan-cum-statement of deduction of tax Section 393(1) 27EQ 143 Quarterly statement of collection of tax at source Section 397(3)(b) 27Q 144 Quarterly statement of deduction of tax on payments to non-residents Section 397(3)(b) 15CA 145 Information for payments to non-resident/foreign company – 15CB 146 Certificate of accountant for payments to non-resident/foreign company – 27BA 150 Form for furnishing accountant certificate Section 398(2) 26AS 168 Annual information statement – Other forms: Form No. (1962) Form No. (2026) Description Section of Act/Rule 3BB 1 Monthly statement to be furnished by a stock exchange in respect of transactions in which client codes have been modified… – 5B 2 Application for notification of a zero coupon bond under section 2(112) of the Act Section 2(112) 5BA 3 Certificate of an accountant under rule 7 Rule 7 3CT 4 Income attributable to assets located in India under section 9(10)(a) of the Act Section 9(10)(a) 3AF 5 Statement regarding preliminary expenses incurred by the assessee to be furnished under Section 44(3) of the Act Section 44(3) 3AE 6 Audit Report under section 44(6) / 51(7) of the Act Sections 44(6), 51(7) 3CG 7 Application for approval of scientific research programme under section 45(3)(c) of the Act Section 45(3)(c) 3CH 8 Order of approval of Scientific Research Programme under section 45(3)(c) of the Act Section 45(3)(c) 3CI 9 Receipt of payment for carrying out scientific research under section 45(3)(c) of the Act Section 45(3)(c) 3CJ 10 Report to be submitted by the prescribed authority to the Chief Commissioner of Income-tax after approval of scientific research programme Section 45(3)(c) 3CK 11 Application for entering into an agreement with the Department of Scientific and Industrial Research for cooperation in In-house research development facility Section 45(2) 3CL 12 Report to be submitted by the prescribed authority to the Chief Commissioner of Income-tax having jurisdiction over the company Section 45(2) 3CLA 13 Report from an accountant relating to in-house scientific research and development facility Section 45(2) 3CM 14 Order of approval of in-house research and development facility Section 45(2) 3CF 17 Application for approval of a company or institution under section 45(3)(b) and 45(4)(b) Sections 45(3)(b) 3CN 18 Application for notification of affordable housing project as specified business Section 46 3CS 19 Application for notification of semiconductor wafer fabrication manufacturing unit as specified business Section 46 3C-O 20 Application for approval of agricultural extension project Section 47(1)(a) 3CP 21 Form for notification of agricultural extension project Section 47(1)(a) 3CQ 22 Application for approval of skill development project Section 47(1)(b) 3CR 23 Form for notification of skill development project Section 47(1)(b) 3CE 24 Audit Report Section 59 3C 25 Form of daily case register – 5C 27 Details of amount attributed to capital asset remaining with the specified entity – 62 29 Certificate from amalgamated company regarding production level – 10-IA 30 Certificate of medical authority for disability, autism, cerebral palsy etc. Sections 127 56FF 33 Particulars to be furnished Section 144 10DA 34 Report for deduction in respect of additional employee cost Section 146 10CCF 35 Report for deduction in respect of Offshore Banking Units Section 147(4)(a) 10CCD 36 Certificate for Authors of certain books in receipt of Royalty Income Section 151(5) 10CCE 37 Certificate for Patentees in receipt of royalty income Section 152(5) 10H 38 Certificate of foreign inward remittance – 10E 39 Form for claiming relief Section 157(1) 10-EE 40 Exercise of option Rule 21AAA(1) 10F 41 Information to be provided Section 159(8) 10FA 42 Application for Certificate of residence Sections 159(1) 10FB 43 Certificate of residence Section 159 67 44 Statement of income from a country or specified territory outside India and Foreign Tax Credit – 3CEFA,3CEFB,3CEFC 49 Application for opting for Safe Harbour – 3CEC 50 Application for a pre-filing consultation – 3CED,3CEDA 51 Application for an Advance Pricing Agreement (APA) – 3CEF 52 Annual Compliance Report on Advance Pricing Agreement – 3CEEA 53 Form for filing particulars of past years for calculating relief in tax payable Section 206(1) 34F 55 Application for invoking mutual agreement procedure in agreements with other countries – 3CEAA 56 Information and document to be furnished by constituent entity Section 171(4) 3CEAB 57 Intimation by
Budget 2026: What It Means for MSMEs in India
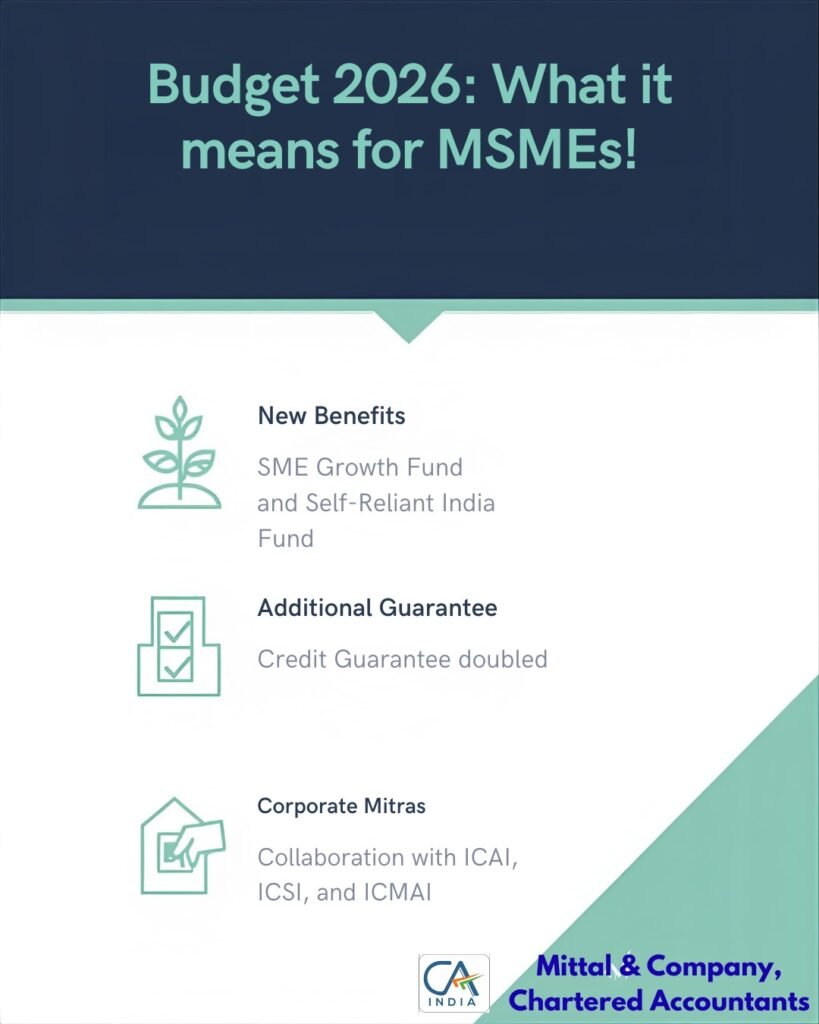
Introduction The Union Budget 2026–27, presented by Finance Minister Nirmala Sitharaman, has once again placed Micro, Small, and Medium Enterprises (MSMEs) at the center of India’s economic growth narrative. MSMEs are vital engines of employment, exports, and supply-chain resilience, and the Budget reflects this by introducing new schemes, strengthening liquidity frameworks, and expanding professional support. At the same time, some long-standing demands, particularly around tax relief and GST simplification remain unaddressed. For MSME entrepreneurs, the Budget offers both immediate opportunities and challenges that will shape their growth trajectory in the coming years. Key Changes for MSMEs Equity and Growth Capital A ₹10,000-crore SME Growth Fund has been announced to provide equity and quasi-equity capital to high-potential MSMEs, especially those with scalability and export potential. The Self-Reliant India Fund receives a ₹2,000-crore top-up, expanding the pool of risk capital. Significance: This marks a shift from debt-heavy support toward growth financing, enabling MSMEs to modernize, expand markets, and compete globally. Stronger Credit and Liquidity Support Credit Guarantee Expansion: Coverage under the Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) has been doubled from ₹5 crore to ₹10 crore, with lower guarantee fees to make borrowing more affordable. TReDS Integration: The Trade Receivables Discounting System (TReDS) is now mandatory for all CPSE procurement from MSMEs. It will also be linked with GeM (Government e-Marketplace), and invoice financing on TReDS will receive credit guarantee support. Impact: These measures aim to reduce payment delays and strengthen working capital cycles, a critical pain point for MSMEs. Professional and Compliance Assistance The Budget proposes collaboration with ICAI, ICSI, and ICMAI to create “Corporate Mitras”- affordable professionals who will guide MSMEs through compliance, accounting, and digital adoption. Relevance: This initiative is particularly valuable for MSMEs in Tier-2 and Tier-3 towns, where access to professional expertise is limited. Higher Classification Thresholds Relaxed investment and turnover ceilings continue to broaden MSME eligibility, allowing more businesses to qualify for credit, subsidies, and procurement opportunities. Missed Expectations No major tax relief or GST reforms were announced, leaving industry calls for simplification unmet. Effective tax rates remain uneven, with non-corporate MSMEs facing relatively higher burdens. Export incentives and digital credit platforms received limited attention, despite strong demand from industry bodies. What MSMEs Should Do Short-Term Actions Leverage New Credit Facilities: MSMEs should explore enhanced CGTMSE coverage and reduced fees to secure affordable loans. Adopt TReDS Early: With mandatory integration for CPSE procurement, MSMEs must familiarize themselves with TReDS to ensure smoother receivables financing. Seek Professional Guidance: Engaging with “Corporate Mitras” can help MSMEs streamline compliance, adopt digital tools, and reduce regulatory costs. Medium-Term Strategies Tap Growth Capital: High-potential MSMEs should position themselves to access the SME Growth Fund and Self-Reliant India Fund by demonstrating scalability and export readiness. Strengthen Supply Chain Integration: With TReDS and GeM integration, MSMEs should align operations to participate more actively in government procurement and large supply chains. Invest in Technology: Equity financing opportunities should be used to upgrade technology, improve productivity, and enhance competitiveness in global markets. Long-Term Considerations Advocate for Policy Reforms: MSMEs must continue to push for tax simplification, GST reforms, and digital credit platforms through industry associations. Focus on Compliance Efficiency: Even without major tax relief, MSMEs can reduce costs by adopting digital accounting, automation, and professional advisory services. Build Global Competitiveness: By leveraging government support and professional networks, MSMEs can gradually position themselves as “Champion MSMEs” capable of competing internationally. Conclusion Budget 2026 places MSMEs firmly at the heart of India’s growth agenda. By expanding access to equity capital, strengthening credit guarantees, and mandating liquidity platforms like TReDS, the government has addressed some of the sector’s most pressing challenges. The introduction of professional support through “Corporate Mitras” further signals recognition of the compliance burden faced by smaller firms. However, the absence of tax relief and GST reforms means MSMEs must continue to navigate complex regulatory landscapes. The true impact of these measures will depend on effective implementation and the ability of entrepreneurs to seize new opportunities. For MSMEs, the path ahead involves balancing short-term wins in credit and compliance with long-term strategies for global competitiveness. In essence, while the Budget does not tick every box, it provides a strategic foundation for MSMEs to strengthen resilience, scale operations, and contribute more meaningfully to India’s economic growth story. For help with Budget 2026 compliance for MSMEs, see our corporate and business taxation services in Pune. BLOG BY – MITTAL & CO.
Budget 2026: Key Changes in Income Tax
Introduction On February 1, 2026, Finance Minister Nirmala Sitharaman presented the Union Budget for the financial year 2026-27. This Budget introduced landmark reforms in direct taxation, focusing on simplification, rationalisation of tax rates, reduction of litigation, and incentivisation of investment. The centrepiece of these reforms is the Income Tax Act, 2025, which will replace the existing law from 1st April 2026. Key Highlights Income Tax Act, 2025 The Income Tax Act, 2025 will replace the Income Tax Act, 1961 from 1st April 2026. The new law has been designed to simplify provisions, reduce ambiguity, and introduce redesigned forms for easier compliance. Changes in TDS Rates Manpower supply services have been clarified as contractor payments, and TDS will now be deducted at 1% or 2%. Property purchases from non-residents will allow resident buyers to deduct TDS using PAN, eliminating the requirement of TAN. Form 15G and 15H can now be submitted to depositories for dividends, interest, and mutual fund income, making compliance easier for small taxpayers. Changes in TCS Rates The rate of TCS on overseas tour packages has been reduced to 2%, compared to the earlier 5% or 20%. The rate of TCS on education and medical remittances under the Liberalised Remittance Scheme (LRS) has been reduced to 2%, compared to the earlier 5%. The rate of TCS on liquor, scrap, and minerals has been increased to 2%. The rate of TCS on tendu leaves has been reduced from 5% to 2%. Following is the detailed table of TCS rate changes: Sl. No. Nature of Receipt Current Rate Proposed Rate 1 Sale of alcoholic liquor for human consumption 1% 2% 2 Sale of tendu leaves 5% 2% 3 Sale of scrap 1% 2% 4 Sale of minerals (coal, lignite, iron ore) 1% 2% 5 Remittance under Liberalised Remittance Scheme (LRS): (a) For education or medical treatment (b) For other purposes (a) 5% (b) 20% (a) 2% (b) 20% 6 Sale of overseas tour programme package (including travel, hotel, boarding, lodging, etc.) (a) 5% up to ₹10 lakh (b) 20% above ₹10 lakh 2% TDS Compliance Changes A fully automated online process has been introduced for issuing lower or nil deduction certificates, particularly benefiting small taxpayers. A one-time disclosure scheme called FAST-DS (Foreign Asset Disclosure Scheme) has been introduced to allow small taxpayers to declare undisclosed overseas assets or income. Changes for Companies (including MAT and other changes) The Minimum Alternate Tax (MAT) has been reduced from 15% to 14%, providing relief to corporates. The set-off of old MAT credit will now be allowed only in the new regime, and it will be capped at 25% of liability. Gains from buyback of shares will now be taxed as capital gains, resulting in higher effective tax for promoters (22% for corporates and 30% for non-corporates). The safe harbour margin for IT services has been fixed at 15.5%, and the threshold has been raised to ₹2000 crore. Changes for Co-operative Societies The scope of deductions available to co-operative societies has been expanded to include those engaged in the supply of cattle feed and cotton seed, thereby supporting rural and agricultural communities. Dividend income earned by one co-operative society from another has been allowed as a deduction under the new regime, encouraging inter-cooperative collaboration and reducing tax burden. Dividend income of notified national cooperative federations has been exempted, provided the investments are made up to 31st January 2026, which strengthens the financial viability of apex cooperative institutions. These measures are designed to empower co-operatives, enhance their competitiveness, and ensure that they continue to play a vital role in supporting farmers, rural entrepreneurs, and community-driven enterprises. Tax Holidays Foreign companies providing global cloud services through Indian data centres will enjoy a tax holiday till 2047. Toll manufacturing in bonded zones will be eligible for a 5-year tax holiday. Global experts working in India will have their non-India income exempt for 5 years. Non-residents under presumptive taxation will be exempt from MAT. Incomes Made Exempt Interest awarded by the Motor Accident Claims Tribunal has been exempted from tax, and no TDS will be required. Disability pensions for armed forces and paramilitary personnel invalided due to disability have been fully exempted. Compensation received from compulsory land acquisition under the RFCTLARR Act, 2013 has been exempted. Capital gains on Sovereign Gold Bonds will be exempt only if they are subscribed at issue and held till maturity. Dividend income of notified national cooperative federations has been exempted for investments made up to 31st January 2026. Updated ITR Changes Pre-filled ITR forms will now cover more categories of taxpayers, reducing errors and simplifying filing. Revised and belated returns can now be filed until 31st March, subject to a nominal fee. Due Date Changes The due date for filing returns for non-audit businesses and trusts has been extended to 31st August. Audit cases will continue to follow the existing timelines. Penalty and Fine A common order for integrated assessment and penalty has been introduced to reduce multiplicity. The immunity framework has been extended to misreporting cases, subject to payment of 100% additional tax. Penalties for technical defaults such as audit reports and transfer pricing reports have been converted into fees. Minor offences have been decriminalised and converted into fines only. The maximum imprisonment for tax offences has been capped at 2 years, with minor offences attracting only fines. New penalties have been introduced for inaccurate reporting of cryptocurrency transactions. Safe Harbour Scheme The safe harbour scheme for IT and IT-enabled services has been updated, with the margin fixed at 15.5% and the threshold raised to ₹2000 crore. This scheme provides certainty in transfer pricing and reduces disputes for large service exporters. Conclusion The Direct Tax proposals in Budget 2026-27 represent a major step towards a simplified and transparent tax regime. With the introduction of the Income Tax Act, 2025, rationalisation of TDS and TCS rates, targeted exemptions, tax holidays for strategic sectors, and decriminalisation of minor offences, the government has created a taxpayer-friendly environment. These reforms
Tobacco Goods- GST to be paid on RSP from Feb 1, 2026
Introduction On January 23, 2026, the Goods and Services Tax Network (GSTN) released an important advisory regarding the reporting of taxable value and tax liability under Retail Sale Price (RSP)-based valuation for notified tobacco goods. This update is highly relevant for businesses engaged in the supply of tobacco products, as it directly impacts how invoices, e-way bills, and GST returns must be reported. Tobacco products have always been under strict regulatory scrutiny due to their high tax incidence and potential for revenue leakage. With this advisory, GSTN aims to ensure uniformity, transparency, and compliance in reporting, thereby reducing mismatches and audit risks. For businesses, this is not just a procedural update—it is a compliance mandate that requires immediate attention. Key Highlights of the Advisory Applicability The advisory applies to notified tobacco goods under GST law. Businesses dealing in such products must adopt Retail Sale Price (RSP) -based valuation instead of transaction value for tax reporting. Scope of Reporting The advisory covers three major compliance areas: e-Invoices – Taxable value and tax liability must be reported on the basis of RSP. e-Way Bills – Movement of goods must reflect RSP-based valuation. GSTR-1 / GSTR-1A / IFF – Outward supplies must be reported consistently with RSP valuation. Purpose of RSP-Based Valuation Ensures uniform taxation across the supply chain. Prevents undervaluation and revenue leakage. Aligns reporting across invoices, transport documents, and returns. Understanding RSP-Based Valuation Retail Sale Price (RSP) valuation means that GST is calculated based on the declared retail sale price printed on the product packaging, which can be same or different from the transaction value between supplier and buyer. For example: If a tobacco product has an RSP of ₹200, the GST liability must be calculated on ₹200, even if the supplier sells it to a distributor at ₹150. This ensures that the tax base remains consistent and prevents manipulation of transaction values. Goods covered: Vide Notification Nos. 19/2025-Central Tax and 20/2025-Central Tax, both dated 31.12.2025, Retail Sale Price (RSP)-based valuation for specified tobacco and tobacco-related products has been prescribed with effect from 01.02.2026. The said notifications cover the following HSN codes and descriptions: 2106 90 20 – Pan masala 2401 – Unmanufactured tobacco; tobacco refuse (other than tobacco leaves) 2402 – Cigars, cheroots, cigarillos and cigarettes, of tobacco or of tobacco substitutes 2403 – Other manufactured tobacco and substitutes; homogenised/reconstituted tobacco; tobacco extracts and essences (other than biris) 2404 11 00 – Products containing tobacco or reconstituted tobacco intended for inhalation without combustion 2404 19 00 – Products containing tobacco or nicotine substitutes intended for inhalation without combustion As per the notifications, valuation of the notified goods is required to be carried out on the basis of the declared RSP. The taxable value for GST purposes is no longer linked to the actual sale price but derived from the RSP printed on the package. Computation of Tax under RSP-Based Valuation For goods notified under RSP-based valuation, tax is computed using the formula: Tax Amount = (RSP × GST Rate %) ÷ (100 + Sum of applicable tax rate) Deemed Taxable Value = RSP – Tax Amount Thus, GST liability is determined with reference to RSP, irrespective of the actual sale price. Example (IGST @ 40%): Total RSP: ₹1,00,000 Tax Amount: ₹28,571.43 Deemed Taxable Value: ₹71,428.57 Commercial transaction values may differ (e.g., net sale value ₹60,000), but statutory tax is always derived from RSP. Existing System Validations Currently, e-Invoice, e-Way Bill, and GSTR-1 systems validate that: Taxable Value + Tax Amount ≤ Total Invoice Value In RSP-based valuation, deemed taxable value plus tax may exceed the commercial transaction value. Hence, special reporting guidance is provided. Reporting Guidance for RSP-Based Valuation Goods For e-Invoice and e-Way Bill: Report Net Sale Value (commercial consideration) in the taxable value field. Report Tax Amount as per RSP formula. Report Total Invoice Value as Net Sale Value + Tax Amount. For GSTR-1 / GSTR-1A / IFF: Report Net Sale Value in taxable value field. Report Tax Amount as per RSP formula (editable if system auto-calculates differently). Report Total Invoice Value as Net Sale Value + Tax Amount. Compliance Requirements Businesses must immediately align their systems and processes with the advisory. Key compliance requirements include: e-Invoice Reporting Ensure taxable value reflects RSP-based valuation. Tax liability must match the notified rules. e-Way Bill Generation Goods in transit must show RSP-based taxable value. Prevents discrepancies between invoices and transport documents. GSTR-1 / GSTR-1A / IFF Filing Outward supplies must be reported with RSP-based values. Ensures consistency across returns and invoices. Risks of Non-Compliance Failure to comply with the advisory can lead to serious consequences: Mismatch Notices – Incorrect reporting may trigger notices from GST authorities. Financial Penalties – Wrong valuation can result in penalties and interest. Audit Red Flags – Tobacco goods are high-risk items for GST audits; errors increase scrutiny. Operational Disruptions – Incorrect e-way bills can delay transportation and supply chain operations. Action Points for Businesses To ensure smooth compliance, businesses should take the following steps: Review Internal Systems Check whether invoicing software applies RSP-based valuation automatically. Update ERP/Accounting Software Configure systems to capture RSP values correctly in e-Invoices and e-Way Bills. Train Staff and Accountants Educate teams on new reporting requirements to avoid manual errors. Cross-Check GSTR-1 Filings Ensure outward supplies match invoices and transport documents. Download and Study the Advisory PDF Refer to the official GST advisory for detailed instructions. Conclusion The GST advisory on RSP-based valuation of tobacco goods is a crucial compliance update that businesses cannot afford to ignore. By mandating RSP-based reporting across e-Invoices, e-Way Bills, and GSTR-1 filings, GSTN has reinforced its commitment to transparency and revenue protection. For businesses, this means revisiting internal systems, updating software, and training staff to ensure accurate reporting. Non-compliance can lead to penalties, audit risks, and operational disruptions. On the other hand, timely adoption of these guidelines will ensure smooth compliance, reduce risks, and build trust with tax authorities. In essence, this advisory is not just a technical update; it is a compliance