📌 Introduction
The Supreme Court of India has delivered a landmark judgment that will have far-reaching consequences for industries across Maharashtra and beyond. By upholding the Bombay High Court’s ruling, the apex court has confirmed that assignment of leasehold rights in industrial land allotted by the Maharashtra Industrial Development Corporation (MIDC) does not attract GST.
This decision provides much-needed clarity for businesses, developers, and investors who have long grappled with uncertainty over whether such transactions constitute a “supply” under GST law. The ruling not only reduces compliance burdens but also strengthens confidence in industrial land transactions, ensuring smoother restructuring and investment flows.
⚖️ Background of the Dispute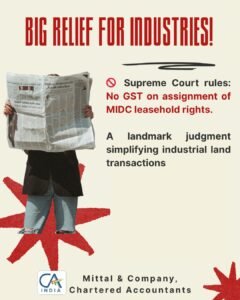
To understand the significance of this ruling, it is important to revisit the context:
- MIDC’s role: The Maharashtra Industrial Development Corporation is a statutory body that allots industrial plots to businesses on a leasehold basis. These plots are critical for setting up factories, warehouses, and other industrial units.
- Assignment of rights: Often, the original allottee of a plot assigns their leasehold rights to another party. This may occur during mergers, acquisitions, or simple business restructuring.
- Revenue’s stance: Tax authorities argued that such assignments amounted to a “supply of service” under GST, thereby attracting tax liability.
- Bombay High Court ruling: The High Court rejected this interpretation, holding that mere assignment of leasehold rights does not constitute a taxable supply.
The Revenue challenged this ruling before the Supreme Court, filing a Special Leave Petition (SLP).
🏛️ Supreme Court’s Observations
The Supreme Court dismissed the Revenue’s SLP, thereby affirming the Bombay High Court’s judgment. The Court’s observations are crucial:
- No automatic GST liability
- Assignment of leasehold rights in industrial land is not a taxable supply under GST.
- The transaction is essentially a transfer of rights already granted by MIDC, not a fresh supply of goods or services.
- Nature of transaction matters
- The Court emphasized that the assignment is a continuation of existing rights, not a new contractual arrangement that creates taxable value.
- Relief for industries
- This ruling removes ambiguity and prevents unnecessary litigation for businesses dealing with industrial land.
- It ensures that industrial transactions are not burdened with additional tax costs that could discourage investment.
📊 Implications for Businesses
The judgment has wide-ranging implications for industries, developers, and investors:
- ✅ Clarity in compliance: Businesses can now confidently assign leasehold rights without worrying about GST liability.
- ✅ Reduced litigation: The ruling curtails disputes between taxpayers and authorities over interpretation of “supply.”
- ✅ Boost to industrial transactions: Easier transfer of leasehold rights will encourage smoother industrial restructuring, mergers, and acquisitions.
- ✅ Investor confidence: By removing tax uncertainty, the ruling strengthens investor trust in industrial land deals.
🔍 Expert Insights
Tax professionals and industry experts view this ruling as a progressive step in aligning GST law with the realities of industrial land transactions.
- Distinction between rights and services: The judgment underscores the importance of distinguishing between transfer of existing rights and provision of new services.
- Precedent for other states: The ruling sets a precedent for similar disputes in other states where industrial development corporations allot land on leasehold terms.
- Policy alignment: It reflects judicial sensitivity to the fact that GST should not be applied in a manner that hampers industrial growth.
📚 Legal Reasoning Simplified
For compliance professionals, the Court’s reasoning can be broken down into simple terms:
- Supply under GST: Defined broadly to include sale, transfer, barter, exchange, license, rental, lease, or disposal made for consideration.
- Assignment of leasehold rights: This is not a fresh lease or license; it is merely a transfer of rights already granted by MIDC.
- Absence of new consideration: Since no new service is being provided, the transaction does not fall within the ambit of “supply.”
Thus, the Court concluded that GST cannot be levied on such assignments.
🏭 Industry Perspective
From an industry standpoint, this ruling is a game-changer:
- Manufacturers and exporters: Can restructure operations without worrying about GST on land transfers.
- SMEs and startups: Gain easier access to industrial plots through assignment, without additional tax burdens.
- Real estate developers: Can plan industrial parks and clusters with greater clarity on tax treatment.
📌 Compliance Takeaways (Quick Reference Table)
| Transaction Type | GST Applicability | Court’s View | Impact on Business |
| Fresh lease from MIDC | GST applicable | Considered supply | Normal compliance |
| Assignment of leasehold rights | No GST | Not a taxable supply | Relief for industries |
| Sale of freehold land | No GST | Land excluded from GST | Standard exemption |
| Transfer during M&A | No GST (if leasehold assignment only) | Covered by ruling | Easier restructuring |
📢 Practical Guidance for Businesses
- Review contracts: Ensure that assignment agreements clearly state that rights are being transferred, not fresh services provided.
- Maintain documentation: Keep MIDC allotment letters, assignment deeds, and court references handy for audit purposes.
- Educate teams: Compliance and finance teams should be briefed on this ruling to avoid misinterpretation.
- Plan restructuring confidently: Businesses can now restructure or transfer industrial plots without factoring in GST costs.
📌 Conclusion
The Supreme Court’s affirmation of the Bombay High Court ruling marks a major victory for industry stakeholders. By holding that assignment of MIDC leasehold rights does not amount to a taxable supply under GST, the Court has provided much-needed clarity and relief.
This decision not only reduces compliance burdens but also strengthens investor confidence in industrial land transactions. For businesses, it’s a reminder that legal clarity can unlock smoother workflows and reduce tax risks.